Option prices constrain a pricing law ; historical dynamics are statements under a physical law . We ask for the set of physical laws consistent with a complete SPX/VIX pricing market and a divergence bound on the pricing kernel. Making the terminal likelihood a coordinate of the carrier turns every physical row and every divergence bound into an affine row on one convex law space. Inside a fixed compact convex adapted-law class, the identified set is then a compact convex fibre with closed graph and measurable selectors; it is nonempty if and only if no finite strict linked separator exists; every continuous affine physical readout has an exact attained interval on it, and conditional-cell forecasts have sharp attained intervals through a separate linear-fractional argument. The bound has three classical instances: an almost-sure density-ratio band with a gain–loss reading, a second-moment band, and a relative-entropy band. Whenever some member of the declared band family restores compatibility, a minimal band width is attained. Under the second-moment band, the two controlled moments minus one are squared Hansen–Jagannathan maximal Sharpe ratios; with the opposite moment cap held fixed and width measured in Sharpe-ratio units, this minimum is the smallest maximal physical Sharpe ratio a compatible kernel must admit, the good-deal bound read in reverse. Worked obstructions and the closed-convex-hull boundary for tests against fixed architectures are included. All results are class-relative: compactness is proved on a finite grid and assumed in continuous time, and we neither point-recover nor claim empirical adequacy of any band.
A rich SPX option surface describes risk-neutral state prices [9]. A time series of returns and option
surfaces describes physical dynamics. Two literatures connect them, and both presume that the object of
interest is a single physical law. Recovery theory asks when option prices determine [46], and its critics
show that the determination rests on structure the data do not supply [8]. The pricing-kernel
bound literature uses security payoffs and returns to restrict the admissible stochastic discount
factors [33]; option-based work derives one-sided or two-sided bounds on a chosen physical
quantity, usually the expected market return [12, 40]. This paper takes the set-valued position
between them: fix the complete SPX/VIX pricing market, fix a divergence bound on the kernel,
and characterize the identified set of linked physical laws, its geometry, and the exact range
of any physical readout on it. Point recovery is the degenerate case in which that set is a
singleton; the bound literature computes one readout’s range under one particular kernel
restriction.
The same object answers a second question. A natural two-stage workflow fits a model
to option prices, fits a model to historical data, and connects their parameters afterward.
Whether or not that workflow is used in a particular implementation, it leaves a logically prior
question:
Can the complete declared SPX/VIX pricing market and the requested physical surface dynamics be carried by one filtered state and one equivalent change of measure?
That is the question of whether the identified set is nonempty, and the answer need not be yes,
as Cheridito et al. [14] already show for affine models; Section 5.3 works out four ways it
can be no. The pricing law may exclude an event required by the physical target. Equivalent
continuous semimartingale laws cannot prescribe different pathwise quadratic variations [37]. A
divergence-bounded likelihood may be unable to move enough mass into a physical stress
scenario [7, 17]. Reduced-state mimicking can preserve one-time marginals without preserving
full-history conditional laws [32], so conditional laws fitted on a reduced state may conflict
with the full market filtration. These are compatibility failures, not failures of a numerical
optimizer.
The key idea. What makes both questions tractable is one change of viewpoint, and it is the contribution of this
paper: a carrier on which the physical law is not a second object but a family of linear rows in the pricing
law. We make the terminal likelihood , its density process, and the forward-variance budget coordinates of
the canonical state, on the same raw filtration as spot and the SPX and VIX surfaces. Then
for every
physical test , so a physical path law is countably many -weighted affine rows, a conditional kernel is the
vanishing of -weighted residuals against a countable algebra generating the observed past,
and a divergence bound is one more affine row; full-history conditioning survives mixing
because the conditioning variables are coordinates. Pricing, physics, and the kernel bound are
thereby linear constraints on one convex set of laws, and the two questions above become the
nonemptiness and the projections of that set. The construction composes two established devices, density weighting under linear constraints [2, 18] and lifting a state so that conditional
constraints become linear [6, 29, 42], into a single system in which the physical rows, the complete
pricing market, and the kernel bound coexist on one filtration; that system is what every
result below is about. The lift is not itself a theorem, since strict equivalence is not weakly
closed, weak convergence need not preserve conditional expectations, and separately fitted VIX
windows need not share one budget; we therefore fix the bridge class before calibration, with one
raw information structure, compactness in a topology preserving full-history rows, and the
band.
Main results. After the lift, every question in the paper is a question about one compact convex set: the fibre of
laws in that match every declared pricing and physical row. The results are the four things one can ask of
such a set: what it looks like, whether it is empty, what it says about a physical quantity, and
what it is a set of. All statements are relative to one fixed compact convex adapted-law class
(Assumption 2.5).
(i)
Geometry. The fibre is compact and convex, the map from targets to fibres has closed graph and one-sided solution-set stability, and it admits Borel and variational selectors (Theorem 4.1). The set of feasible targets is itself compact and convex. Compactness and convexity are not decoration: the separation argument of (ii) and the support-function representations of (iii) both live on them, and both are supplied by the lift rather than assumed of the market.
(ii)
Existence. The fibre is nonempty if and only if every finite determining panel is feasible, if and only if no finite strict linked separator exists, the physical terms of the separator being -weighted expectations under the same pricing law as its pricing terms (Theorem 5.2). Emptiness therefore always has a finite witness. On a finite panel the witness is a violated support inequality (Proposition 5.3); on a finite grid, where compactness is proved rather than assumed, it is a pathwise certificate with explicit gain, moment, and band multipliers (Proposition 5.4). Section 5.3 shows what witnesses look like: a band that cannot move enough mass, a pricing support that excludes a physical event, or covariance characteristics prescribed twice. The third is bracket invariance under equivalent change of measure (Proposition 5.7), and Remark 5.9 records that it is at once the hypothesis licensing current joint work and the constraint on it.
(iii)
Inference. On a nonempty fibre, every continuous affine physical readout has an exact attained identified interval, with dual slice-endpoint formulas on a finite panel (Proposition 6.2), and every conditional cell forecast has a sharp linear-fractional range whose endpoints are zeros of affine support-oracle problems (Proposition 6.3). The answer can be an interval rather than a point because, on an atomless carrier and without further class restrictions, finitely many physical moments need not identify the likelihood (Proposition 6.1). Such rows carry sensitivity analysis under a bounded density ratio onto a martingale-constrained law class, where each bound is a constrained optimization rather than a sort. The band is the hinge between (ii) and (iii): widen it and the fibre appears, narrow it and the intervals tighten. Whenever the declared band family contains a compatible member, the smallest width at which a compatible bridge exists is attained, also for a compact target uncertainty set (Proposition 6.5). Under the second-moment band, the two controlled moments minus one are squared Hansen–Jagannathan maximal Sharpe ratios (Lemma 2.7); holding the opposite moment cap fixed and measuring width in Sharpe-ratio units makes this threshold the smallest maximal physical Sharpe ratio any compatible kernel must admit, the good-deal bound read in reverse. In three states the three bands select three different fibre points (Example 6.9).
(iv)
Scope. The fibre is a set of laws in , not of models in a chosen family . A linear support test against a fixed family is a sound rejection test, but nonrejection certifies only membership in the closed convex hull of the family’s quote image (Proposition 7.1), so a good or bad fit of one architecture settles neither compatibility nor market-level conflict. Whether a selected finite model is locally identified is a separate, chart-level question (Proposition 7.5) that does not make the law-level fibre a singleton.
The band and its readings. The band that runs through these results is where the class meets practice. Since is affine for any , the
bound is convex automatically and weakly closed when is lower semicontinuous, and the compatibility
theorem holds for any superlinear . Three choices are classical. An almost-sure band implies the
gain–loss restriction of Bernardo and Ledoit [7]; the ratio-only restriction is recovered by
allowing the normalized endpoints to vary at a fixed ratio. A second-moment band is the
Hansen–Jagannathan class: is the squared maximal physical Sharpe ratio, so capping it is the
good-deal restriction of Cochrane and Saá-Requejo [17]. A relative-entropy band bounds on one
side and on the other. With as benchmark and as the distorted law, the second has the
robust-control orientation of Hansen and Sargent [34]; the first is the reverse-KL mirror. The second is
also the objective of entropic joint calibration [29, 30]. The almost-sure band is the sharpest
but is violated by every model whose likelihood is unbounded or has essential infimum zero,
as with Gaussian-mixture innovations and a shifted drift; any model whose likelihood has
finite moments of the required orders lies inside the moment and entropy bands at sufficiently
large levels. We state results for a general band and record the three readings where they
differ.
What is not claimed. The generality of the band does not extend to the class: every result is class-relative. Compactness and
adapted closure are proved on a finite grid in Section 5.2 and assumed in continuous time; they are not
consequences of the Radon–Nikodym identity, and Assumption 2.5 is the main gate for any concrete
continuous carrier. We do not point-recover from option prices, establish that historical SPX/VIX data
satisfy any band, turn every separator into a traded arbitrage, identify a bridge from finitely
many moments, or compute on data. The alternative theorem is short by design: once the
carrier and rows are built, existence is finite intersection plus finite-dimensional separation,
and the contribution is the carrier that makes that argument available and the readings it
supports.
Relation to the literature. That contribution is best located against three literatures that address this question or a neighbour of
it. Recovery theory asks option prices to determine [35, 46]; Borovička et al. [8] show that the
determination rests on structure the data do not supply, and its empirical record is weak [36]. We
give the set that remains when that structure is dropped. The Hansen–Jagannathan bound
restricts the kernel using security-market payoffs and returns [33]; option-based bounds target
physical quantities such as the expected market return [12, 40]. We bound any continuous affine
readout, two-sidedly and sharply, on the full SPX/VIX carrier and under a divergence ball rather
than a covariance sign; the price is that our intervals are sharp only inside a declared class,
whereas the negative correlation condition of Martin [40] needs almost nothing. Joint modelling
asks when one state carries both dynamics, parametrically in Cheridito et al. [14] and in the
estimation literature [5, 15, 26, 43], and most recently for SPX/VIX in Guyon and Parent [31],
who compare option values generated from a -estimated model with market prices and report
structured residuals that they read as a possible tail risk premium. We ask the same question
nonparametrically on a declared filtration, and is the scalar such a residual calls for. Kernel estimation
[20, 48] selects one bridge or one projection; our fibre may remain set-valued. The pricing-kernel
puzzle [19] is the documented tension that motivates asking whether a linked pair exists at
all.
The paper builds on two lines. The alternative theorem is a carrier-level convex-feasibility analogue in
the lineage of the good-deal fundamental theorem of Staum [51], anticipated by Černý and Hodges [53]: it
uses the same separation logic on a carrier that holds the complete SPX/VIX pricing market, the
likelihood and its density process as coordinates, and full-history physical rows. This is not a
specialization of the traded-payoff theorem, because some of the present separator’s rows are not traded.
The identified intervals carry the marginal sensitivity model of Tan [52] and Dorn and Guo [24], with
its sharp conditional bounds by fractional programming, from covariate-wise reweighting to
a martingale-constrained law class, where each bound is a constrained optimization rather
than a sort. The complete pricing market itself is the object built by entropic joint SPX/VIX
calibration [29, 30], which we take as given on the pricing side and extend to the physical
side.
Organization. The paper follows the order of the main results. Section 2 builds the canonical market, the band with
its three readings, and the bridge class; Section 3 encodes physical laws as affine rows and defines the
fibre. Sections 4 to 7 then answer the four questions of the main results in order: the geometry of the
fibre (Section 4); its nonemptiness, with computable certificates and the three obstructions (Section 5);
inference on it, from nonidentification through exact intervals to the minimal divergence, with a finite-grid
illustration (Section 6); and its scope against fixed architectures and selected charts (Section 7).
Section 8 concludes.
2Canonical market, band, and bridge class
2.1Carrier, structural law, and linked pair
Fix a horizon and one VIX tenor , and put . Let be a Polish enhanced path space with coordinates
Here
is continuous log spot, is a continuous nondecreasing clock normalized by , is a continuous nonnegative
forward-budget field for , and are cadlag raw price-surface processes with maturity domains and ,
respectively, and are frozen after maturity. The coordinate is a terminal likelihood and is a cadlag
density process. All roots are deterministic. The raw filtration contains exactly the coordinates revealed
through ; is revealed only at . The surface coordinates are raw price processes as in dynamic
option-surface models [11, 39, 49].
Set
Definition 2.1 (Divergence band) . A band is a pair of nonnegative lower semicontinuous functions and
levels such that
A law on satisfies the band when
Three instances are used below. The almost-sure
band takes equal to the convex indicator of , with and , so that (5) reads -a.s. The moment band takes
and with and . The entropy band takes and , both nonnegative and convex; when these rows are the
relative entropies and of Lemma 2.4.
For compact minimal-width families we also use the closed extension of the almost-sure
instance. The boundary is the singleton band ; strict inequalities are what give slack around that
likelihood.
Since is a coordinate, and are affine on the space of laws, so (5) consists of two affine inequality rows.
Lower semicontinuity and nonnegativity make both rows weakly closed by the Portmanteau theorem; the
growth of makes uniformly integrable over any family satisfying (5) by the de la Vallée-Poussin criterion;
and the growth of forces almost surely in every weak limit. These three properties are the only ones the
compatibility proofs use, so the almost-sure band is a special case rather than the general
object.
Definition 2.2 (Structural pricing law) . Fix a band. A law on is structural when, in the completed raw
filtration:
(i)
, , and are true martingales;
(ii)
is interval additive and
(iii)
for and , respectively, the frozen processes and are true martingales with terminal values
(iv)
, is a true martingale, , and satisfies the band (5).
All conditional statements are tested against bounded functions of the full raw past, not merely the current
spot.
Proposition 2.3 (Self-contained pricing-side interface) .If is structural and , then is a positive true
-martingale, , and every declared VIX window is generated by the same additive bracket budget. Moreover,
for and ,
and (6) supplies the corresponding conditional bracket increments. Thus Definition 2.2is the
complete pricing-side input used below; no separate pricing theorem is invoked in the compatibility
proofs.
Proof.Since is continuous, adapted, increasing, and starts at zero, it is predictable. Continuity of
, together with the local martingales and , therefore identifies with by uniqueness of predictable
quadratic variation. Moreover, ; the separate row makes this stochastic exponential a true rather
than merely local martingale. Each raw surface process is a true martingale stopped at its maturity
and has the terminal value in (7); the defining property of conditional expectation gives (8). Interval
additivity and (6) give the common budget assertion.∎
Lemma 2.4 (Linked pair) .For structural , define
Then is a probability law, , and
Their completions
of coincide, and the pathwise quadratic variation of remains under .
Proof.The martingale property gives . For , , proving (10). Finiteness of gives a.s., and finiteness
of with gives a.s.; hence with common null sets. Quadratic variation is pathwise and invariant
under an equivalent change of measure.∎
2.2The bridge class
Assumption 2.5 (Adapted-compact bridge class) . There is a metrizable adapted-law space and a
nonempty compact convex subset such that:
(a)
every is structural on the same raw canonical filtration, with the same deterministic roots and the same band ;
(b)
dominates weak convergence and preserves all declared full-history conditional rows;
(c)
an inf-compact envelope satisfies almost surely under every and , and each unbounded row below, pricing or -weighted physical, obeys for some ; for the almost-sure band the first requirement is vacuous, since almost surely under every law of the class;
(d)
every target-row expectation below is continuous on .
The band rows contribute to (c) and (d) but do not deliver them. Coercivity of at infinity and of at
zero makes the marginal law of tight and uniformly integrable, so every physical row with a
bounded continuous integrand is continuous under weak convergence with no further hypothesis;
for unbounded integrands the envelope condition in (c) does the same work. What the band
cannot supply is tightness of the path coordinates or closure of the full-history conditional
rows. Coordinate tightness needs modulus estimates, and preservation of conditioning on
the full past needs an adapted or extended-weak closure argument. Assumption 2.5 is the
main class-verification gate. In finite discrete time the several natural adapted topologies
agree [3], adapted distances give a useful stability notion for finance [4], and compactness has an Arzelà–Ascoli-type characterization rather than an ordinary Prokhorov criterion [25].
Those results do not supply a compactness theorem for the present continuous-path carrier. In
continuous time, adapted compactness and preservation of the declared conditional rows remain the
topology-specific obligations assumed in Assumption 2.5; marginal tightness alone is not sufficient. On
the finite grid of Section 5.2, compactness is instead proved directly in the ordinary weak
topology.
Remark 2.6 (Nonemptiness and the pricing-side interface) . Nonemptiness of means that at least
one structural pricing carrier exists before the additional physical targets are imposed. The interface
is explicit in Definition 2.2 and Proposition 2.3. An external construction, such as a joint SPX/VIX
calibration [28–30], may be used to establish nonemptiness and adapted compactness only after
matching every item of Assumption 2.5; those properties are not inferred from individual option
surfaces, the divergence band, or the Radon–Nikodym identity.
2.3Economic meaning of the band
The band is a declared overlap class, not an assertion that the true market likelihood satisfies it. Its
economic content depends on which band is chosen, and the three instances of Definition 2.1 have three
classical readings.
Almost-sure band. For every event ,
For a future event and current history,
so
with sharper history-dependent
denominators in place of the outer band. The class imposes common scenario support and caps every
probability distortion pointwise. The fixed envelope implies a gain–loss cap : Bernardo and Ledoit [7]
bound the ratio of the essential extrema of the normalized pricing kernel . Their ratio-only restriction does
not fix and separately; conversely, it is the union of normalized envelopes with below the
cap. The variable-endpoint family in Proposition 6.5 implements that union. These algebraic
gain–loss statements concern the stipulated class of claims valued by ; a market interpretation
for a smaller attainable payoff span requires a separate trading-space argument. The fixed
envelope is the most restrictive of the three bands for the tail-support reason recorded in
Remark 5.9.
Moment band. With zero rates the stochastic discount factor is up to normalization. For the moment band with , the
two controlled moments minus one are the two Hansen–Jagannathan variances, equivalently the squared
maximal Sharpe ratios in (14).
Lemma 2.7 (Maximal Sharpe ratios from likelihood second moments) .Let with , , and . Over bounded
payoffs with positive variance, with the convention that the supremum is zero if this class is empty,
Proof.Since , the numerator of the first ratio is ∎
which Cauchy–Schwarz bounds by ; unless the
variance of is zero, the bound is approached by the bounded truncations , which converge to in .
If that variance is zero, -a.s., hence and every numerator is zero; the supremum is zero whether
the admissible class is nonempty or is empty under the stated convention. Now , and . The second
identity is the same argument with the roles of and exchanged, using and .
The first identity is the Hansen–Jagannathan bound [33]: on the stipulated space of all bounded claims
valued by , the cap is exactly the restriction that no such claim has physical Sharpe ratio above . It yields
the good-deal restriction of Cochrane and Saá-Requejo [17]; on a smaller traded payoff span it is sufficient
but need not be necessary. The second identity is its mirror under the pricing measure. Under the moment
band the pointwise bounds (11) are replaced by Hölder bounds: for every event ,
The upper bound is
Hölder applied to . For the lower bound, write
and apply Hölder with exponents and . These are
weaker per event than (11), which is the price of a class that admits models with unbounded
innovations at large enough levels; the exact interval of Proposition 6.2 below is sharp under either
band.
Entropy band. Under the -row is and the -row is . With as benchmark and as the distorted law, the latter has the
robust-control orientation of Hansen and Sargent [34]; the former is its reverse-KL mirror. The -row is the
one calibration practice minimizes: entropic calibration of a candidate to the option surface with as prior
minimizes , in weighted Monte Carlo [2] and in martingale Schrödinger bridges [29, 30, 42]. In those
problems the prior is fixed and the entropy is minimized; here both sides are bounded across the bridge,
and the minimal bound over the compatible fibre, defined in Proposition 6.5, is a Schrödinger-type value
for the linked pair.
In every case the reciprocal change-of-measure component is related to a stochastic discount factor
only after a numeraire and normalization are fixed, and no band is a preference model.
Strict equivalence is not weakly closed without uniform overlap. On , for let
Then but , a singular
pair; the likelihood is at state and at state , so and both diverge and the sequence leaves every
band of Definition 2.1. This is what the two band rows are for: the -row keeps uniformly
integrable, and the -row keeps it away from zero in the limit. Sending the levels to infinity
through separately solved problems does not prove attainment in an unrestricted equivalent-law
class.
3Physical laws as affine rows
Let be a declared observable path coordinate, such as the pair of raw SPX and VIX surface processes,
taking values in a Polish space . Fix bounded convergence-determining functions . A target physical path
law is encoded by
For a conditional target, let be a Polish-valued future coordinate and a Borel kernel from the stopped
raw history. Take a bounded convergence-determining family and a countable multiplicative algebra of
bounded full-history functions containing constants and generating . Impose
for every and
.
Lemma 3.1 (Meaning of the physical rows) .For , equations (17) for all are equivalent to . Equations
(18) for all are equivalent to
Proof.The identity turns (17) into equality of integrals under two probability laws. The
convergence-determining family separates them. It turns (18) into , where . The functional
monotone-class theorem extends from to every bounded -measurable multiplier, so . Countable
determination identifies the kernel. The converses follow by conditioning.∎
Testing only functions of would identify conditioning on their sigma-field, not on the full
market history. Equality requires a separately proved sufficient-state property. Reweighting a
simulated ensemble by to match finitely many price rows is the operational ancestor of these rows
[2].
Let enumerate countably many continuous affine rows on : dense SPX/VIX pricing rows and the
-weighted physical rows above. Let be their targets.
Assumption 3.2 (Countable determination) . The enumeration determines the complete declared
SPX/VIX quote surfaces, the physical path law, and each physical conditional kernel. Parameter
continuity extends dense maturity, strike, and time rows to their full domains.
Definition 3.3 (Compatible-law fibre) .
Each certificate induces the linked pair .
4Geometry of the identified set
This section answers the first of the four questions of the introduction: what the identified set looks like.
The answer is that it is a compact convex fibre with a closed graph, and that this geometry is inherited
from the lift rather than assumed of the market.
Equip with its product metric, write , and set .
Theorem 4.1 (Stable compatible-law fibres) .is compact and convex. The graph of is closed. If , , and metrizes on , then
There is a Borel selector with .
Proof. is continuous and affine, hence has compact convex image. Its inverse fibres have a
closed graph. If (21) failed, a subsequence would remain at positive distance from . Compactness
gives a further subsequence converging to , and graph closedness gives , a contradiction. The
inverse correspondence has nonempty closed values. If is open, write with compact. Then
∎
is Borel because every is compact. Thus the correspondence is weakly measurable, and the
Kuratowski–Ryll-Nardzewski theorem supplies a Borel selector.
The stability is one-sided solution-set stability, not Hausdorff continuity. It gives no inverse rate. It is
also weaker than what is available in the pricing-only problem: in their one-step real-line setting, for
martingale measures with fixed marginals, Neufeld and Sester [41] prove full lower and upper
hemicontinuity in the marginals by a set-valued map argument. We do not claim the two-sided statement
here, because the -weighted physical rows and the full-history conditional rows are not marginal
restrictions and the corresponding lower hemicontinuity is not established for the class of Assumption 2.5.
If is proper and lower semicontinuous and finite somewhere on a feasible fibre, compactness gives an
-minimizer. A continuous strictly convex gives a unique Borel selector. Entropy is one possible criterion
under its own domain and lower-semicontinuity conditions [18, 42]; the raw market does not identify that
choice.
5Existence: finite witnesses
This section answers the second question: when the fibre is nonempty, and what a witness
of emptiness looks like. Theorem 5.2 gives the finite alternative; Sections 5.1 and 5.2 give
computable certificates on a finite panel and on a finite grid; and Section 5.3 exhibits the three
obstructions.
For finite , let
Definition 5.1 (Finite strict linked separator) . A finite strict linked separator is a finite set and
coefficients such that
Physical terms on the left are -weighted expectations under the same canonical
pricing law as the pricing terms.
Theorem 5.2 (Complete linked alternative) .Under Assumptions 2.5and 3.2, the following are
equivalent:
(a)
;
(b)
one equivalent pair on the declared filtered state, whose enhanced -law belongs to , carries the complete structural SPX/VIX market under , satisfies all physical targets under , and whose likelihood satisfies the band (5);
(c)
for every finite ;
(d)
there are satisfying for ;
(e)
no finite strict linked separator exists.
When feasible, is compact and convex. When infeasible, a finite collection of declared pricing and physical
rows witnesses failure.
Proof.Lemmas 2.4 and 3.1, the structural settlements, and countable determination prove (a)(b).
Clearly (a) implies (c), and (c) implies (d). Under (d), compact metrizability gives a convergent
subsequence . For fixed , all sufficiently large terms fit row ; continuity gives . Thus .
If (a) holds, no separator can integrate to a strict inequality. If (a) fails, the finite-intersection
property for the closed sets gives finite with . The image ∎
is compact and convex, while . Strict
finite-dimensional separation yields (23). The fibre is a closed affine section of compact convex .
Once the carrier and rows are built, the proof is short by design: the work has been moved into the
lifted formulation, whose adapted compactness and row closure are the substantive obligations. The
argument places the theorem in the lineage of full-versus-finite-subsystem consistency in linear
semi-infinite optimization [27] and of the good-deal fundamental theorems [1, 51], the martingale
selection problem [10, 44], and finite-panel realizability [21], now on a carrier that holds both
laws.
5.1Finite-panel support criterion
For a finite panel, separate the pricing and physical integrands as and , so
For define
Proposition 5.3 (Finite support criterion) .The finite target is attainable if and only if
The maximum
is attained. If the target is infeasible, one violates (26) strictly.
Proof. is a compact convex subset of finite-dimensional Euclidean space. The assertion is its
support-function representation and strict separation from an exterior point.∎
5.2Pathwise certificate on a finite grid
For a pathwise refinement, fix dates and a closed Polish finite-grid carrier . Its histories include and . Let
and be continuous next-step residual vectors. Let consist of finite sums
with bounded continuous
multipliers. Take a band with finite on , as for the moment and entropy bands. For continuous
inf-compact and , define
Inf-compactness of on already forces as any tends to or ; the two band rows are separate affine
inequalities with their own levels. For a law on this carrier, set
Assume that some satisfies all three caps
in (28) strictly, and that, for some ,
The likelihood weight now appears explicitly because is
no longer bounded. For example, by Young’s inequality, (30) follows from separate power
dominations and with , together with the analogous -domination of , , and the density increments
.
Proposition 5.4 (Pathwise finite certificate) .If lies outside , there are , multipliers , , and such that
Conversely, such a tuple proves infeasibility. Only finitely many conditional rows occur in . For the
almost-sure band, restrict the carrier to , drop the two band rows, and set ; the statement and proof are
then those of the bounded case.
Proof.Inf-compactness and make weakly compact; the two band rows are weakly closed because and
are nonnegative and lower semicontinuous, so is compact and convex. Condition (30) makes every
displayed expectation, including the -weighted ones, uniformly integrable and hence continuous, so is
compact and convex. Thus is compact and convex, and strict separation gives with a positive support
gap. With , let
Give the Hausdorff quotient the locally convex topology generated by the evaluation
maps , . Sion’s theorem, with the compact convex class as its compact argument, gives
For an
inadmissible law, scaling a violated gain makes the inner infimum ; an admissible law annihilates every
gain. Sion’s theorem applies because every expectation is finite and continuous under (30)
[50].
For fixed , put . The envelope gives . For caps , define ∎
The three constraints are affine in , so is
concave and nondecreasing in each argument, and it is finite and attained wherever its feasible set is
nonempty, by the compactness just established. The Slater law places in the interior of the domain, so
has a supergradient there. For any the Dirac law is feasible at the caps , so the supergradient inequality
gives
Taking the supremum over yields the reverse of weak duality, hence
The multiplier infimum in (34)
is attained by the supergradient just constructed. The outer infimum over in (33) need not be attained;
nevertheless the strict support gap allows a choice of , followed by its attaining multipliers, whose
value lies inside that gap. Taking equal to the inner supremum gives (31)–(32). Conversely,
integrating (31) under a calibrating law annihilates , uses the three caps, and contradicts
(32).
The band multipliers are the finite-grid form of the statement that the band is itself a row: a
certificate may charge part of the violation to the divergence constraint, and the pair records how
much. When both vanish, the target is infeasible for reasons that no widening of the band can
repair.
The witness is mathematical, not automatically a traded arbitrage: physical rows and the coercive
penalty need not be traded claims. A literal arbitrage interpretation requires a separate superhedging
implementation and, with it, the standard no-free-lunch machinery relating admissible strategies to
equivalent martingale measures [22]. This is a substantive difference from the pricing-side certificates of
Guyon [29], which are traded portfolios.
5.3What witnesses look like
Example 5.5 (Two-state band obstruction) . Let , with pricing target and physical target . Both are
valid probability laws and are equivalent, but their unique density is
They are incompatible with and .
The explicit separator is
Compatibility is restored exactly when and . The obstruction is joint: neither
marginal law is invalid.
The same unique density has and . By Lemma 2.7, the maximal risk-neutral and physical Sharpe
ratios of the only candidate bridge are therefore and ; the latter can be read directly from the single
payoff , whose physical excess mean is and physical standard deviation . A good-deal cap on the physical Sharpe ratio below is an obstruction of the same kind under the moment band, with the band row itself
as the violated row.
Example 5.6 (Support failure) .Let be a stress event. Suppose the pricing carrier forces , whereas
a separately fitted physical law requires . Then
because -a.s. No can link the two, under
any band. Enlarging a parameterization without enlarging the pricing support cannot fix the
problem.
Proposition 5.7 (Bracket and covariance-characteristic invariance) .Let on a common completed
filtration and let be a continuous vector semimartingale under both laws. Its matrix quadratic covariation is the same under and , up to indistinguishability under either law. In particular, if predictable
positive-semidefinite processes and satisfy
then -a.e. and -a.e. Diffusion factorizations need only obey ;
the factors themselves need not coincide.
Proof.Quadratic covariation is determined pathwise by the coordinate trajectories, with cross terms
obtained by polarization. Equivalent laws have the same null sets, so their quadratic-covariation
versions coincide. Uniqueness of the Lebesgue density of the resulting finite-variation matrix
measure gives the equality of and . Equality of diffusion covariances follows from the
quadratic-covariation formula; predictable orthogonal rotations show why equality of chosen square
roots is unnecessary.∎
and, for a fixed shift , put . If has density ,
then and
If , the essential infimum of is zero and its essential supremum is infinite. Consequently, for
independent innovations and any fixed finite sequence of shifts, the product likelihood has moments of
every real order; if at least one shift is nonzero, it has the same essential-extrema property. The moment
conclusion also holds for predictable history-dependent shifts whose absolute values are uniformly bounded
over the finite horizon.
Proof.The likelihood normalization follows by translation. Since is a convex combination of the
numbers , the mean-value theorem gives, uniformly for , ∎
A finite Gaussian mixture has every
exponential moment of , proving (39), uniformly for . If , Gaussian tail dominance yields as ;
the two tails therefore give zero and infinity when . Independence proves the fixed-shift product
statements, and conditioning backwards with the uniform one-step moment bound proves the last
assertion.
Remark 5.9 (The same invariance is a bridge and an obstruction) . Proposition 5.7 is not a
technicality peripheral to applied practice; it is the hypothesis on which the leading empirical
attempt in this market rests. Guyon and Parent [31] justify comparing a -estimated path-dependent
volatility model with option data precisely by observing that, in a continuous-time diffusive setting,
an equivalent change of measure does not alter the volatility coefficient, so a model estimated
from returns should already approximate the pricing dynamics up to drift. That is the present
proposition, read forwards.
Read backwards it is a constraint. The invariance that licenses the comparison also forbids
independently prescribed - and -covariance characteristics on one carrier: a two-stage workflow that
fits a pricing model with characteristic and then, separately, a physical model with has produced
an infeasible pair, whatever residual its optimizer reports. The two readings are the same theorem.
Which one is operative depends on whether the volatility coefficient is estimated once and shared,
or twice and reconciled afterwards.
The empirical comparison in Guyon and Parent [31] estimates model parameters separately and
does not itself construct an equivalent linked pair or its Radon–Nikodym derivative. A deliberately
linked, fixed-parameter drift-shift bridge built with their finite Gaussian-mixture innovation would
instead fall under Lemma 5.8, provided the standardized shifts satisfy its hypotheses. Such a bridge
is excluded from every almost-sure band when a shift is nonzero, while it belongs to the moment and
entropy bands at sufficiently large levels. The two properties do different work: unbounded support
of rules out an almost-sure band, whereas moment or entropy membership additionally requires the stated integrability. Neither property of an actual empirical pair may be inferred before that
pair and its common innovation law have been constructed.
Example 5.10 (Quadratic-variation obstruction) .Suppose the pricing carrier requires almost surely for
a scalar covariance rate , while a continuous-path physical target requires
Every equivalent bridge on the
carrier instead has . More generally, Proposition 5.7 rules out independently prescribed - and -covariance
characteristics. It does not require literal equality of diffusion factorizations: and give the same
covariance for a predictable orthogonal rotation .
Remark 5.11 (Drift changes and compatibility distance) .Suppose, in addition, that a common
Brownian filtration and a density representation have been verified. With one fixed sign convention for the
density, Girsanov then gives a drift displacement of the form
Hence even the drift displacement is
restricted to the range of ; it is not a free coordinate. The stochastic exponential must be a true
martingale and satisfy the integrability and likelihood conditions of the declared bridge class.
Neither a formal choice of nor a local-martingale density establishes an admissible linked
pair.
An isolated projection of covariance estimates onto equality is elementary only after both estimates
have been aligned on the same state, clock, and filtration. For example, under a declared weighted
Hilbert metric, positive weights , and aligned covariance characteristics , the pointwise diagonal
projection is
The formula projects , not a chosen square root , and changes with the metric
and weights. Separately fitted - and -models may not possess a common state alignment at
all, in which case the pointwise formula is undefined. The useful global object is instead a
distance, under a declared metric, from the complete target to the compatible data/quote image .
Computing that distance must enforce jointly the support, likelihood, raw-filtration, price, bracket,
and other structural rows defining . No such numerical or empirical projection is claimed
here.
Example 5.12 (Why ordinary weak convergence is insufficient) .Let be symmetric on , , and .
Then reveals and . In the weak limit , its natural sigma-field is trivial and the corresponding
conditional mean is . Marginal weak convergence has lost information. This motivates adapted row
closure in Assumption 2.5.
6Inference on the identified set
This section answers the third question: what a nonempty fibre says about a physical quantity. The result
is an identified set; without further likelihood-class restrictions, finitely many physical moments need not
make it a point (Proposition 6.1). Its projection onto any continuous affine readout is an exact
attained interval (Section 6.1); and, whenever the declared band family contains a compatible
member, the band is the hinge at which the fibre appears, with an attained minimal width
(Section 6.2).
Proposition 6.1 (Finite physical moments do not identify a likelihood) .Let be atomless and bounded.
There are distinct bounded positive normalized likelihoods such that
They may be chosen inside any band
of Definition 2.1that has slack at : for some , and on . For the almost-sure band this holds
whenever ; for the moment band it is the strict slack and , and for the entropy band it is and
.
Proof.Choose a nonzero bounded function orthogonal in to the finite span of . Such a bounded
simple function exists by partitioning an atomless space into more positive-mass cells than the
number of restrictions. For small , put . Orthogonality to constants normalizes the two densities,
and orthogonality to each gives (43). For both densities take values in , so they are positive and
satisfy and pointwise, hence the band.∎
The slack condition cannot be dropped. At zero slack a strictly convex row is at its Jensen minimum:
a zero entropy cap, or a moment cap , forces almost surely, so the likelihood is identified
and . A physical readout then equals its counterpart and is identified by the pricing rows
only when those rows determine that counterpart. Proposition 6.1 shows that, absent further
class restrictions on the likelihood, a band containing an neighborhood of leaves directions
invisible to every finite moment panel; a particular declared class can still eliminate those
directions.
The proposition separates compatibility, selection, and identification. A nonempty fibre answers the
first question. Entropy or another criterion chooses a point for the second. Only sufficient observations
plus a valid inverse argument answer the third.
6.1Exact identified intervals
We next give the identified set of a readout, in the sense of partial identification [16], and separate it from
the simpler band envelope. Let be any continuous affine readout and, for a feasible target , put
Proposition 6.2 (Exact compact-fibre identified interval) .The identified set of is exactly the attained
compact interval
For a finite panel , define the augmented support oracle
Proof.The fibre is nonempty, compact, and convex. Its continuous affine image in is therefore
an attained compact interval. For the upper formula, weak duality gives on the slice. Conversely,
strictly separate from the compact convex augmented image . The coefficient of the final coordinate
is positive because belongs to that image; normalize it to one and let . Apply the same argument
to for the lower formula.∎
For a readout with whose - and -readout rows are continuous, take and write and .
The band alone gives only an outer envelope: under the almost-sure band,
and under the
moment band, by the Hölder argument of (15),
If the quote rows fix , the first reduces to , so
positive physical means differ by at most . These band endpoints need not themselves be attainable; the exact interval is (45) or, for a finite panel, (47), and it is sharp under every
band.
Conditional forecasts require a different optimization.
Proposition 6.3 (Sharp conditional cell range) .Let be a bounded -measurable history weight and let be
a bounded future readout. Suppose
are continuous affine rows and . Then the exact identified set of the
cell forecast
is an attained interval . Its upper endpoint is the unique zero of
and its lower endpoint is the
unique zero of
Thus each trial value of requires an affine support-oracle evaluation. The zero
characterization is the parametric fractional-programming device of Dinkelbach [23]; one-dimensional
bisection is one valid root solver. For a finite-panel fibre, each oracle evaluation has the dual
representation (47) with .
Proof.The denominator bound makes continuous on the compact fibre, so its extrema are attained;
its image is an interval because a ratio of affine functions with positive denominator maps every line
segment continuously and monotonically between its endpoint ratios. For any , . At the maximal
ratio the maximum in (51) is zero; it is positive below and, using , strictly negative above. The
lower formula is identical with minimum in place of maximum. The objectives are affine, so the
last claim follows from Proposition 6.2.∎
For and a history cell whose -probability is fixed at , (50) is , and the positive-denominator
hypothesis holds under every band of Definition 2.1. The almost-sure band supplies and the moment
band supplies by (15). For a general band put , which tends to infinity as by (4); Markov’s inequality
gives , hence
A point-history forecast additionally requires a common version and continuity of
evaluation at that history; a band on the terminal likelihood alone does not provide either
condition. Proper scoring, selector choice, and prequential evaluation are separate statistical
questions.
Remark 6.4 (Relation to sensitivity analysis under a bounded density ratio) . The device of this
section is a new application, to a martingale-constrained law class, of sensitivity analysis under
a bounded density ratio. A two-sided bound on a density ratio between a target law and a reference law, used to convert a point estimand into an identified interval, is analogous to the
marginal sensitivity model of Tan [52], an extension of the propensity-odds sensitivity model
of Rosenbaum [45]. The causal model bounds a conditional propensity-odds ratio, whereas our
global, generally asymmetric band bounds itself. If the latter is parameterized symmetrically
as , its gain–loss endpoint ratio is , not . In that literature the interval for a mean is obtained
by linear-fractional programming [54], and the sharp version of the bound is due to Dorn
and Guo [24]. The one-dimensional root-finding step in Proposition 6.3 uses the parametric
zero characterization of Dinkelbach [23]. For a finite-dimensional linear-fractional program, the
Charnes–Cooper substitution is a distinct one-shot LP reformulation [13]. Readers who know that
literature will recognize Propositions 6.2 and 6.3 as its instance on the compatible fibre.
What is new is the constraint set. In sensitivity analysis the reweighting is constrained
only by covariate-wise normalization, so each bound is a sort or an explicit quantile-balancing
formula. Here the reweighted law must simultaneously remain in : one raw filtration, a single
additive forward-variance budget, true-martingale spot and surface rows, settlement identities, and
full-history physical conditional rows. Every evaluation of the support oracle in (46) is therefore
a martingale-constrained optimization over an adapted-compact law class rather than a pointwise
reweighting, and the resulting interval is a statement about the compatible fibre, not about a
reweighting of a fixed sample. The transplant is what makes the sensitivity parameter interpretable
as a gain–loss cap or a maximal Sharpe ratio rather than as unmeasured confounding. The
divergence bands of Definition 2.1 likewise have a sensitivity-analysis counterpart: the -sensitivity
model of Jin et al. [38] constrains an -divergence generated by the relevant likelihood ratio, and its
counterfactual-mean bounds admit distributionally robust dual formulations. The global moment
and entropy rows here are finance-side analogues, not the same causal restriction.
6.2The minimal compatible divergence
Band sensitivity is meaningful only if the nonband ingredients are held fixed. Accordingly, let be one
compact parent class satisfying the structural, topology, envelope, and row-continuity requirements above
with the band rows omitted, and let be a family of bands indexed by a compact parameter set , with and
jointly lower semicontinuous, with levels continuous, and nested in a specified partial order: implies that
every law satisfying the band at satisfies it at . For the almost-sure band, ranges over , where , and
means and . For the moment band, ranges over a compact box contained in , with the
usual product order; for the entropy band it ranges over a compact box contained in , again
with the usual product order. Define
so that
Fix a continuous width , nondecreasing in the
specified order. For the almost-sure band, . For the moment band with and the -level held
fixed, take a compact slice and the natural Sharpe width . The domain starts at one because
every feasible equivalent pair satisfies by Jensen’s inequality. For the entropy band, vary
the selected level from its Jensen lower bound, either or , while holding the opposite level
fixed.
with the convention .
Whenever , this infimum is a minimum and is attained. For a compact uncertainty set of
target vectors, define analogously after replacing by ; whenever finite, its infimum is likewise
attained.
Proof.The likelihood coordinate is continuous on the canonical carrier and is nonnegative and
lower semicontinuous, so is lower semicontinuous on by the Portmanteau theorem applied to the
joint laws ; likewise for . Since are continuous, and its counterpart are lower semicontinuous, so the
set of satisfying both band rows is closed. Upper semicontinuity of would suffice here; continuity
is what the instances provide. Intersecting with the closed row constraints gives a compact feasible
graph inside , whose projection onto is compact, possibly empty. If it is nonempty, the continuous
function attains its infimum there; if it is empty, the stated convention gives . Adding a compact
target uncertainty set preserves the same argument.∎
Remark 6.6 (Three readings of ) . Under the almost-sure band, when finite, is the minimal gain–loss
ratio that restores compatibility; in Example 5.5, if the widest envelope contains the unique density, .
Under the moment band with , fix the opposite cap and write
Extend by . For the compact
slice described above, whenever is finite,
Indeed, the objective in (58) is extended lower
semicontinuous, and (57) is compact, so the displayed minimum is attained. Any feasible point of
the compact slice shows that the minimizing inverse moment is at most ; choosing at a
minimizing law then proves the equality with the band-width problem. Finiteness forces -a.s.; the minimizing law therefore defines an equivalent pair, and Lemma 2.7 identifies its
objective with
with the empty-class convention of that lemma. Thus (58) is the smallest maximal
physical Sharpe ratio that any compatible pricing kernel satisfying the fixed opposite cap
must admit. This is the good-deal bound of Cochrane and Saá-Requejo [17] read in reverse,
with the option surface and the physical rows as inputs and the Sharpe cap as output. In
Example 5.5 it equals , because conditional randomization of given the state cannot lower
, by Jensen’s inequality. Under the entropy slices anchored at zero above, with , whenever
finite, is the minimal over the compatible fibre, the orientation of entropic calibration; with ,
whenever finite, it is the minimal . Either is a Schrödinger-type value for the linked pair.
The three thresholds are different numbers selecting different fibre points, as Example 6.9
shows.
Remark 6.7 (The bridge literature as a special case) . Under the entropy slice with , an exact
reduction to a standard entropic calibration requires more than point identification of the physical
rows. Let denote the entire common declared market-history carrier, before the pair-dependent
coordinates and are adjoined. Assume that the physical restrictions fix one full law on , not merely
finitely many of its moments, and let be the intended pricing-feasible class on that same carrier.
For each candidate , the relevant object is its canonical linked lift, which appends and its density
process. Suppose the -projection of every relevant lift in belongs to , and an ordinary minimizer
exists, is equivalent to , admits a linked lift in satisfying all the nonband rows, and obeys the
fixed opposite cap and the slice bound . If, conversely, every has a canonical lift in satisfying all
nonband rows, the fixed opposite cap, and , the two feasible classes agree exactly; for equality of
the minimum it is enough that the displayed minimizer has such a lift. Under these conditions the
opposite cap is nonbinding at the standard solution and
This is entropic calibration to the option
surface with the historical law as prior, the martingale Schrödinger-bridge orientation [2, 30, 42].
The present framework includes that corner under the stated lifting conditions, while also allowing
to be set-valued, a moment rather than entropy band, and existence or range questions rather than
selection. Existing entropic calibration machinery computes the present only when it enforces the
declared parent class, every nonband row, and the fixed opposite cap.
The threshold is class-relative but not ambiguous: all nonband conditions come from the single parent
. Enlarging the band increases every support value and weakly decreases every fixed-direction separator
gap. A reported empirical threshold must also disclose , the band family and width , the target
uncertainty set, and the normalization of .
Remark 6.8 (What would measure on a reported residual panel) . The intended use of is not to
adjudicate whether a joint fit succeeded, but to put a scalar on the gap that a successful-looking fit
leaves behind. A concrete instance is available in the literature. Guyon and Parent [31] estimate a
path-dependent volatility model under from index returns alone and compare its implied pricing
quantities with a market panel across many dates. Their reported disagreement is small in aggregate
but signed and structured: model implied volatilities below the market for short- to medium-dated
out-of-the-money index options and above it at the longest maturity, and below the market for
large-strike VIX options. They suggest this pattern may reflect a volatility tail risk premium.
Such a panel of signed residuals, together with bid–ask and sampling tolerances, can be encoded
as a compact target uncertainty set in the sense of Proposition 6.5 only after a common linked carrier, its row map, and a parent class have been specified. The empirical comparison in
Guyon and Parent [31] does not itself construct that linked pair. Once those ingredients are
supplied, and whenever , the proposition gives the attained smallest divergence level consistent
with the panel inside the declared ; under the moment band, by (58), it is a maximal Sharpe
ratio. Reporting that number would replace a qualitative statement that two measures are close,
or that a residual looks like a premium, with a disclosed quantity on a disclosed class, in units the
good-deal literature already uses. We emphasize what this would and would not settle. It would
not show that the residual is a risk premium rather than misspecification, and by Proposition 7.1
a threshold computed against one architecture is architecture-relative. It would bound how large
a kernel distortion, in gain–loss, Sharpe-ratio, or entropy units, any compatible bridge must
carry to reproduce the observed panel. Lemma 5.8 verifies the required moment integrability only
for the deliberately linked fixed-parameter drift-shift construction described in Remark 5.9; it
does not place the separately estimated empirical comparison inside a band. No such empirical
computation is performed here. Besides Assumption 2.5 on a continuous carrier, it first requires
the linked construction and every pricing and physical row. A fully specified finite-grid carrier,
where compactness is direct, is one tractable route; Section 6.3 supplies only a synthetic proxy
calculation.
Example 6.9 (An analytic bridge fibre with a strict band envelope) . On a one-date carrier let
have fixed pricing probabilities . Hold all other structural coordinates fixed, impose , and
require the physical row . For any compatible lifted law define the conditional likelihood means
Normalization and the physical row give, for some scalar ,
The band forces , and conversely every
such point is attained by taking . Hence the exact identified interval for the physical success
probability is
whereas the generic band envelope based only on is the strictly wider . If the band
is allowed to vary while the pricing and physical rows remain fixed, minimizing the largest
conditional likelihood mean divided by the smallest in (59) gives
Randomizing conditionally on
cannot improve this ratio, because every admissible lower bound is no larger than the smallest
conditional mean and every admissible upper bound is no smaller than the largest conditional
mean.
The central moment and entropy orientations also select different points. For the Sharpe width of
Remark 6.6,
This strictly convex function has its unique minimum on at , the unique root in that
interval of
where
At this point , so any fixed opposite moment cap strictly above that value is
nonbinding. The mirror moment criterion
is instead minimized at , where its value is ; at the gain–loss
optimum its value is .
For the entropic-calibration orientation,
has its unique minimum at
There , so a fixed reverse-entropy
cap strictly above this value is nonbinding. The reverse-KL mirror is itself minimized at the
root of . Conditional randomization of given cannot lower any of these four criteria, by
conditional Jensen applied to , , , and . Thus the compact fibre, its exact readout interval, the
loose band envelope, and the three central minimal widths—gain–loss, physical Sharpe, and —are distinct objects even in three states; their opposite-orientation mirrors are distinct as
well.
6.3A finite-grid illustration
The exact finite-carrier setting of Section 5.2 is computable as stated. The synthetic calculation below
implements the lifted convex geometry and an exact discrete counterpart of all three structural martingale
identities in Definition 2.2. It is a finite quoted panel rather than a complete continuous option surface,
and it is not evidence about any market.
Setting. On a finite path set the substitution represents the lift of Section 2: one optimizes jointly over two
probability vectors on the same paths, the pricing weights and the physical weights. Every declared pilot
pricing row is linear in , every physical row is linear in , and the prefix ratios define the discrete density
process. The three bands become linear inequalities, rotated second-order cones, and exponential cones,
respectively. The moment and entropy widths each require one conic program. Every finite conic value is
recomputed from a residual-verified primal witness; its global optimality is based on solver
status, without a separately checked dual certificate. The displayed recovery endpoints are
likewise raw-primal-verified solver-status optima; no independently checked endpoint dual
certificate is claimed. The gain–loss width is a bisection on over linear programs after the
substitution . Numerically it uses the exact complete pricing-fibre reduction and , then checks the
reconstructed probabilities against every original row. Every finite reported gain–loss value is a
verified-feasible upper bound on , and the largest solver-reported-infeasible trial lies within of
it.
The carrier is a non-recombining hybrid tree over six trading days with steps ( paths, nodes), on
which volatility follows the four-factor path-dependent recursion of Guyon and Parent [31] at their
published parameters. Its finite innovations are constructed for the present structural identities and are
not their Gaussian mixture. At a node put , , , and . An ordinary node has , where solves
with
probabilities . Consequently , , and exactly. One node at the final step instead has , , with positive
symmetric pair masses solving and . This node is chosen so the terminal call rows add at most one local
rank. At every ordinary node, normalization and the local structural rows have rank three, so
root-to-leaf induction pins all ordinary transitions. Once normalization and all structural and
quoted rows are imposed, the remaining complete affine pricing fibre is , where is supported on
the special node and ; the archive contains an explicit distinct positive pricing law in this
fibre. Thus is predictable and , , and are exact discrete martingales, while is genuinely
set-valued.
The pilot imposes sparse structural rows, SPX calls at the horizon and at its midpoint, the date-zero
budget row, budget rows at each of the midpoint nodes with tenor days, so that is a node coordinate, a
VIX future and VIX calls written on it: quoted and budget rows in all, with . The physical rows are a
conditional-mean row at every node, which fixes one of the two free conditional probabilities at an
ordinary node. A variant adds standardized conditional powers through one less than the local child count; together with normalization these rows have full Vandermonde rank and pin
every physical transition, including the six-way node. The pricing weights, and with them ,
remain set-valued. The remaining rows are a crash probability , and a terminal-return second
moment, all taken from a fixed physical law calibrated at every node to and given a tail
tilt. In the path-level crash stress displayed in the left panel below, the conditional rows are
dropped and the second-moment row is replaced by the mean terminal gross return, so the other
path target remains fixed. The code reproduces the analytic calculations in Examples 5.5
and 6.9 to a maximum relative deviation of , commensurate with the bisection tolerance of
.1
Sharpe widths are in six-day units throughout; the annualization factor is about .
Figures 1 and 2 numerically instantiate the same interval and minimal-width optimizations as
Propositions 6.2 and 6.5 on this explicitly declared exact finite structural fibre.
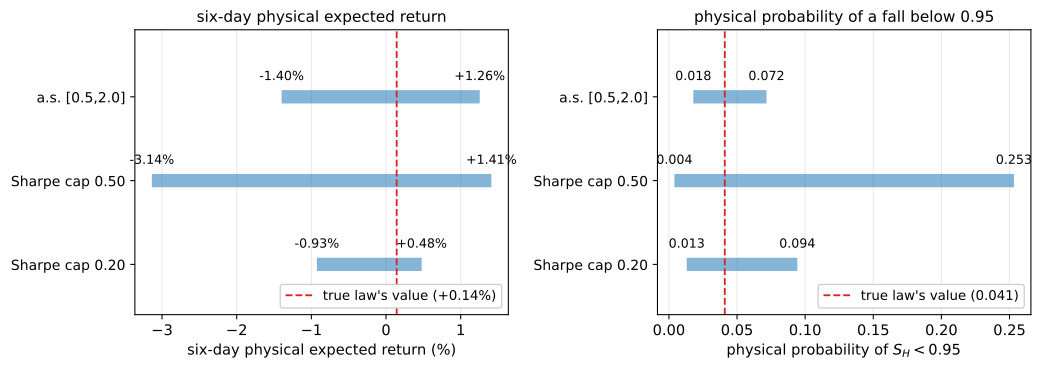
Figure 1. Set-valued recovery from option prices alone. Identified intervals for two physical readouts under three bands, with no physical rows declared. The true law’s two readout values lie inside every interval, including under the cap , which excludes the true law itself (its kernel has Sharpe width ): each value is attained by some feasible law with a smaller kernel. Once the physical rows are added the minimal distortions are gain–loss on (a verified upper bound; see Table 1), Sharpe width , and , each below the true kernel’s , , and , because the rows do not pin the kernel. With the full local-moment rows added, the physical transition weights and hence the physical market-path projection are pinned. The enhanced-carrier law is not point-identified, because its and coordinates vary with the still set-valued pricing weights; the Sharpe width rises to .
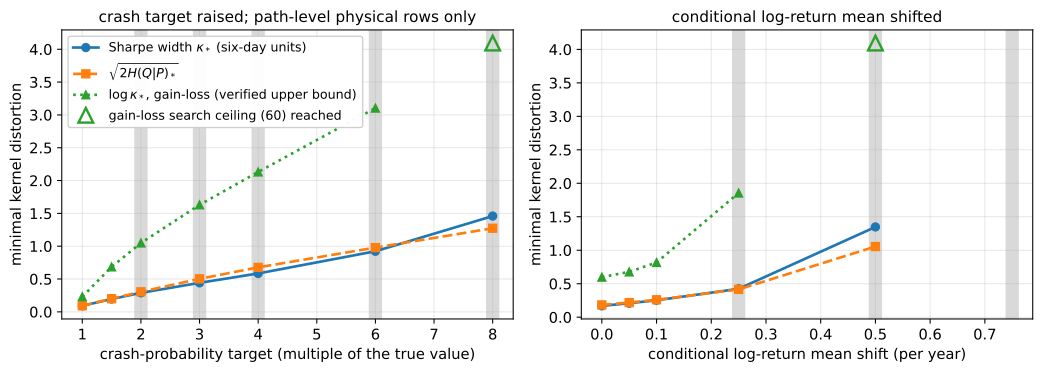
Figure 2. The band as hinge. Minimal kernel distortion as the physical target moves away from the pricing data: Sharpe width, , and for the gain–loss band. Every finite gain–loss point is a verified-feasible upper bound; open triangles mark the search ceiling , hence censoring rather than infeasibility. Grey bars mark targets at which the fixed-band LP reports infeasible, a solver-status rather than certificate-checked verdict. Left: the crash target is raised with only the path-level crash and mean terminal-return rows; right: the conditional mean log return at every node is shifted by a constant annualized amount. For the left panel, a direct LP with an archived primal–dual certificate places the fixed-band wall at times the true crash probability. For the right panel, the transition lies in per year of added conditional mean log return: the lower endpoint has a verified feasible witness and the upper endpoint is solver-reported infeasible without a separately checked Farkas certificate.
Discretization and reproducibility. Table 1 refines the same six-day horizon with steps ( paths; seconds for the base block) and records
the solver settings. Trees at different step sizes are not nested, so this is a sensitivity test rather than
convergence along a refining sequence. The true kernel’s width and the displayed expected-return recovery
interval are stable across the three grids, whereas the crash probability and its recovery intervals are not.
The Sharpe and entropy minima decrease across the three displayed grids, whereas the gain–loss
minimum is stable but nonmonotone. Because the grids are not nested, these patterns are
reported as observed sensitivity and are not explained by any inclusion of fibres; the spreads are
shown rather than summarized. Tree, pricing law, and physical law are synthetic, and the
computation on a reported residual panel remains the open step named in Remark 6.8. What the
illustration establishes is that the declared finite structural fibre is computationally workable,
that the Sharpe width and agree to second order at small distortions and differ by up to
at the largest stresses (the gain–loss width is a different functional and is not compared),
and that the two emptiness mechanisms of this paper are distinguishable in this synthetic
experiment.
In the unplotted crash stress that retains the conditional-mean rows, all three bands fail
beyond the direct-LP support wall times the true target because the conditional rows, retained
terminal-return second-moment row, and finite branch support jointly bound the crash probability: a
support obstruction rather than a band obstruction. The wall has an archived primal–dual
certificate.
Table 1. Discretization
sensitivity
at
a
fixed
six-day
horizon,
and
solver
settings.
item
value
steps
(paths)
()
exact
structural
carrier
three martingale rows at every node; independent mean/full checks on the three grids, with largest conditional residual
true
kernel
Sharpe
width
(spread )
true
kernel
(spread )
true
crash
probability
(spread )
Sharpe
width
,
physical
rows
added
(spread )
entropy
,
physical
rows
added
(spread )
gain–loss
,
physical
rows
added
(spread )
recovery
of
,
band
lower ; upper
solvers
Python 3.14.0, cvxpy 1.8.2, CLARABEL 0.11.1, SCS 3.2.11, HiGHS through scipy 1.17.0. Gain–loss ratio LPs: HiGHS through the SciPy interface, three 30 s attempts (automatic method selection, dual simplex, then interior point), then CLARABEL, then SCS; other LPs CLARABEL then HiGHS; cone programs CLARABEL with default settings, then tightened tolerances, then equilibration disabled, then SCS, re-solving until a point verifies
verification
gain–loss ratio LPs: a feasible verdict requires a primal residual of at most on every row and band inequality, whatever the solver reports; fixed-band feasibility LPs: ; Sharpe and entropy programs: affine equalities are row-normalized for conditioning, then the raw returned vectors are checked against the original rows for nonnegativity, linear rows, and simplex within , closed-perspective zero pairs within , the opposite-side cap within a relative , and scaled objective error ; cold-start re-solves continue until a point verifies; the finite conic objectives are primal-verified solver-status optima, not independently dual-certified; each JSON record references a unique archive containing the raw witnesses and diagnostics for every finite reported solution
known-witness
guard
on all base and refinement grids, the independently reconstructed true laws satisfy every active row with residual at most ; each gain–loss search must be uncensored and its verified upper trial cannot exceed the true likelihood-ratio width by more than the bisection tolerance
tolerances
solver defaults on first attempts and the fallback settings just described; gain–loss bisection relative with ceiling
caps,
nonnegativity,
and
closed
perspectives
opposite-side cap in the Sharpe and entropy programs; no strictly positive mass floor is imposed, and the raw returned weight vectors are checked directly for nonnegativity within the stated primal-residual tolerance; moment and entropy terms use their exact closed perspectives; the entropy epigraph uses the exact substitution , , and objective or cap ; a numerical zero denominator is accepted only when its paired numerator is at most ; no logarithmic smoothing is used
statuses
over the archived base, full-physical-row, and stress A/B/C records (recovery intervals, refinement, and validation excluded): logical optimization calls (solver attempts), invoked a fallback solver, obtained their verdict on a fallback, exhausted the chain unresolved and were treated as infeasible, ended optimal_inaccurate, and cone-program solutions were flagged by the recomputation check and are reported with that flag; the affected gain–loss widths are therefore verified-feasible upper bounds; the largest solver-reported-infeasible trial lies within of each, infeasibility verdicts being taken from solver status without a certificate check
infeasibility
residuals
smallest phase-1 gap at a reported infeasibility (unscaled; reported without further inference)
7Scope: architectures and charts
This section answers the fourth question: what the fibre is a set of. It is a set of laws in . A fixed
architecture inside sees only its closed convex quote hull (Section 7.1), and identification of a selected
finite model is a separate, chart-level tier (Section 7.2).
7.1Architecture boundary: the closed convex quote hull
Proposition 5.3 is exact because the declared law class has a compact convex quote image. A fixed
parametric or structural architecture need not share that geometry. Let be any nonempty
declared architecture and put
where is the number of pricing and physical rows in the finite
panel.
Proposition 7.1 (Linear tests see the closed convex quote hull) .For every finite target ,
Consequently,
a strict violation of one support inequality validly proves , whereas satisfaction of every inequality proves
only closed-convex-hull membership. The support test characterizes exact membership in the architecture
for every target if and only if is closed and convex.
Proof.A continuous linear functional has the same supremum on a set and on its closed convex
hull. Finite-dimensional strict separation characterizes the complement of that closed convex set,
proving (70). Since , a strict violation also excludes the original architecture. Exact equivalence for
every target holds precisely when the two sets coincide.∎
Example 7.2 (False reassurance from nonconvexity or nonclosure) . If an architecture has scalar
quote image , the target zero is not attainable, but it satisfies every support inequality because it
lies in the convex hull. This is a failure of completeness, not a false rejection: any strict separator
would still exclude both the hull and the architecture. Closure is a separate issue. For quote image
, the target zero again satisfies every support inequality and has distance zero from the image, yet
no model attains it. Thus convexity without closedness is insufficient, and a residual alone does not
certify exact membership.
Remark 7.3 (A scoped convexification diagnostic) . Fix a disclosed weighted norm on the finite panel
and a market uncertainty set containing, for example, bid–ask and sampling bands. Define
For a singleton target and dual norm , the hull residual is itself the maximal normalized support
violation,
The gap measures relaxation by convexification only relative to the declared panel, norm,
uncertainty set, and architecture. Computing is the original global nonconvex problem. The hull
problem is an LP or convex program only when its finite representation or a globally valid
support oracle is available; an LP over a sampled parameter grid sees only the sampled hull and
cannot exclude unsampled models. If the quote image is nonclosed, may still coexist with exact
nonattainment.
For nested classes , a component-order diagnostic must report the whole residual curve and, at
tolerance , may define
This panel-relative order is not an intrinsic factor or predictive-state dimension.
Convexifying mixes whole models and can add regimes or internal components, so the single number
does not answer how many components the market “requires.”
One possible response is to replace by a separately verified tagged or randomized enlargement. That
converts hull points into admissible models only when the enlarged class genuinely preserves the
common root, all affine pricing and physical rows, the likelihood restrictions, and the declared
filtration after the tag becomes observable. It changes the architecture and its complexity; it
does not prove membership in the original . Otherwise exact architecture feasibility requires
a separate global nonlinear membership method. No architecture gap is computed in this
paper.
7.2Selected-chart identification is a separate tier
Let and let map a gauge-fixed finite model parameter to its enhanced canonical law. Gauge fixing
removes local label permutations, unreachable states, and other law-preserving symmetries. For a finite
panel , set
Assumption 7.4 (Law/chart interface) . On a neighborhood of :
(a)
lies in the same , including its raw filtration, common budget, density rows, and band;
(b)
is one-to-one modulo equality of the induced linked pair;
(c)
every coordinate of is a canonical row, not a surrogate observation from a different model;
(d)
is , its derivative is -Lipschitz, and
This is an interface assumption, not an imported realization theorem. A model-specific
application must prove that its chart maps into , that its observations are the canonical rows,
and that its derivative has the stated regularity and rank. Generic rank theory is classical
[47].
Proposition 7.5 (Chart-relative local inverse) .If and
with when , then for ,
Thus the selected
chart is locally identified by . The conclusion does not imply that the full law-level fibre is a
singleton.
Proof.For , integrate the derivative along the segment and subtract . The Lipschitz condition and
(75) bound the remainder by . The singular-value margin bounds the leading term below by . Hence
, proving (76).∎
Rank failure produces a first-order null direction and invalidates this inverse modulus; it does not
automatically prove exact nonidentification. The fallback is an identified set, a null-direction
analysis, or more observations. A regularized optimizer is a selector, not evidence that the data
identify its output. Conversely, local injectivity of the selected chart does not make global
linear support tests exact for the generally nonconvex image ; that question remains subject to
Proposition 7.1.
8Conclusion
Within one fixed compact convex adapted-law class with a divergence band on the likelihood, the linked
laws consistent with a complete SPX/VIX pricing market form a compact convex fibre, nonempty exactly
when no finite linked separator exists, on which every continuous affine physical readout has an exact
attained interval. Every statement is relative to that class. On a finite grid its compactness is
proved (Section 5.2); in continuous time it is Assumption 2.5, and constructing a nonempty
adapted-compact continuous SPX/VIX carrier is the one proof obligation this paper leaves
open.
The practical message is compatibility before calibration. A failed joint fit can reflect an optimizer, a
chosen architecture, noisy targets, or a genuine conflict between physical and pricing requirements; the
fibre and its finite separators isolate the last, and architecture-level claims require the hull diagnostic of
Section 7.1. When compatibility holds, what remains are decisions the market does not make: how the
class is justified, which point is selected, and what further model and data assumptions identification
needs.
The symmetric message applies to an apparent success. Current joint work reports aggregate
agreement with signed, maturity- and strike-dependent residuals read informally as risk premia [31], and
Remark 5.9 notes that the invariance licensing those comparisons is the one constraining them. A
structured residual of that kind is a statement about the likelihood, and the likelihood admits a
disclosed scalar summary on a disclosed class. Computing on a reported residual panel is the
natural next step and the point at which the framework becomes empirically informative. It first requires an equivalent linked pair, verification of the chosen moment or entropy bounds,
and a parent carrier carrying every pricing and physical row. The exact structural finite-grid
pipeline of Section 6.3 is an engineering template for that exercise, not yet the empirical
application.
AI-use disclosure. The author used Anthropic Claude Code and OpenAI Codex as interactive research and writing tools.
They assisted with exploratory discussion, testing and refinement of ideas, literature and source
organization, code development and verification, mathematical error checking, and editorial
revision.
Notes
Code, scope, raw output, and the generated numbers used here are in the pilot directory of the source
archive. ↩
References
[1] Maria Arduca and Cosimo Munari. Fundamental theorem of asset pricing with acceptable risk in markets with frictions. Finance and Stochastics, 27(3):831–862, 2023. doi: 10.1007/ s00780-023-00509-x.
[2] Marco Avellaneda, Robert Buff, Craig Friedman, Nicolas Grandchamp, Lukasz Kruk, and Joshua Newman. Weighted Monte Carlo: A new technique for calibrating asset-pricing models. International Journal of Theoretical and Applied Finance, 4(1):91–119, 2001.
[3] Julio Backhoff-Veraguas, Daniel Bartl, Mathias Beiglböck, and Manu Eder. All adapted topologies are equal. Probability Theory and Related Fields, 178(3):1125–1172, 2020. doi: 10.1007/s00440-020-00993-8.
[4] Julio Backhoff-Veraguas, Daniel Bartl, Mathias Beiglböck, and Manuel Eder. Adapted wasserstein distances and stability in mathematical finance. Finance and Stochastics, 24: 601–632, 2020.
[5] Chris Bardgett, Elise Gourier, and Markus Leippold. Inferring volatility dynamics and risk premia from the S&P 500 and VIX markets. Journal of Financial Economics, 131(3):593–618, 2019.
[6] Mathias Beiglböck, Pierre Henry-Labordère, and Friedrich Penkner. Model-independent bounds for option prices: A mass transport approach. Finance and Stochastics, 17(3):477–501, 2013. doi: 10.1007/s00780-013-0205-8.
[7] Antonio E. Bernardo and Olivier Ledoit. Gain, loss, and asset pricing. Journal of Political Economy, 108(1):144–172, 2000. doi: 10.1086/262114.
[8] Jaroslav Borovička, Lars Peter Hansen, and Jose A. Scheinkman. Misspecified recovery. Journal of Finance, 71(6):2493–2544, 2016.
[9] Douglas T. Breeden and Robert H. Litzenberger. Prices of state-contingent claims implicit in option prices. Journal of Business, 51(4):621–651, 1978.
[10] Matteo Burzoni and Mario Šikić. Robust martingale selection problem and its connections to the no-arbitrage theory. Mathematical Finance, 30(1):260–286, 2020. doi: 10.1111/mafi. 12225.
[11] Rene Carmona and Sergey Nadtochiy. Local volatility dynamic models. Finance and Stochastics, 13:1–48, 2009.
[12] Fousseni Chabi-Yo and Johnathan Loudis. The conditional expected market return. Journal of Financial Economics, 137(3):752–786, 2020. doi: 10.1016/j.jfineco.2020.03.009.
[13] Abraham Charnes and William W. Cooper. Programming with linear fractional functionals. Naval Research Logistics Quarterly, 9(3–4):181–186, 1962. doi: 10.1002/nav. 3800090303.
[14] Patrick Cheridito, Damir Filipović, and Robert L. Kimmel. Market price of risk specifications for affine models: Theory and evidence. Journal of Financial Economics, 83(1): 123–170, 2007.
[15] Mikhail Chernov and Eric Ghysels. A study towards a unified approach to the joint estimation of objective and risk neutral measures for the purpose of options valuation. Journal of Financial Economics, 56(3):407–458, 2000.
[16] Victor Chernozhukov, Han Hong, and Elie Tamer. Estimation and confidence regions for parameter sets in econometric models. Econometrica, 75(5):1243–1284, 2007.
[17] John H. Cochrane and Jesús Saá-Requejo. Beyond arbitrage: Good-deal asset price bounds in incomplete markets. Journal of Political Economy, 108(1):79–119, 2000.
[18] Imre Csiszár. -divergence geometry of probability distributions and minimization problems. Annals of Probability, 3(1):146–158, 1975.
[19] Horatio Cuesdeanu and Jens Carsten Jackwerth. The pricing kernel puzzle: Survey and outlook. Annals of Finance, 14(3):289–329, 2018. doi: 10.1007/s10436-017-0317-9.
[20] Jeroen Dalderop and Oliver Linton. Estimating a conditional density ratio model for asset returns and option demand. Journal of Econometrics, 254(B):106191, 2026.
[21] Mark H. A. Davis and David G. Hobson. The range of traded option prices. Mathematical Finance, 17(1):1–14, 2007. doi: 10.1111/j.1467-9965.2007.00291.x.
[22] Freddy Delbaen and Walter Schachermayer. A general version of the fundamental theorem of asset pricing. Mathematische Annalen, 300:463–520, 1994.
[23] Werner Dinkelbach. On nonlinear fractional programming. Management Science, 13(7): 492–498, 1967. doi: 10.1287/mnsc.13.7.492.
[24] Jacob Dorn and Kevin Guo. Sharp sensitivity analysis for inverse propensity weighting via quantile balancing. Journal of the American Statistical Association, 118(544):2645–2657, 2023. doi: 10.1080/01621459.2022.2069572.
[25] Manu Eder. Compactness in adapted weak topologies. arXiv:1905.00856, 2019.
[26] Bjorn Eraker. Do stock prices and volatility jump? reconciling evidence from spot and option prices. Journal of Finance, 59(3):1367–1403, 2004.
[27] Miguel A. Goberna and Marco A. López. Linear Semi-Infinite Optimization. Wiley, Chichester, 1998.
[28] Ivan Guo, Grégoire Loeper, Jan Obłój, and Shiyi Wang. Joint modelling and calibration of SPX and VIX by optimal transport. SIAM Journal on Financial Mathematics, 13(1):1–31, 2022.
[29] Julien Guyon. Dispersion-constrained martingale Schrödinger problems and the exact joint S&P 500/VIX smile calibration puzzle. Finance and Stochastics, 28:27–79, 2024.
[30] Julien Guyon. Dispersion-constrained martingale Schrödinger bridges: Joint entropic calibration of stochastic volatility models to S&P 500 and VIX smiles. SIAM Journal on Financial Mathematics, 16(3):834–874, 2025. doi: 10.1137/22M1511242.
[31] Julien Guyon and Léo Parent. Reconciling - and -calibration: The discrete-time 4-factor path-dependent volatility model. SSRN working paper 5382733, 2026. First posted 2025; revised 2026.
[32] István Gyöngy. Mimicking the one-dimensional marginal distributions of processes having an Itô differential. Probability Theory and Related Fields, 71:501–516, 1986. doi: 10.1007/BF00699039.
[33] Lars Peter Hansen and Ravi Jagannathan. Implications of security market data for models of dynamic economies. Journal of Political Economy, 99(2):225–262, 1991.
[34] Lars Peter Hansen and Thomas J. Sargent. Robust control and model uncertainty. American Economic Review, 91(2):60–66, 2001. doi: 10.1257/aer.91.2.60.
[35] Lars Peter Hansen and Jose A. Scheinkman. Long-term risk: An operator approach. Econometrica, 77(1):177–234, 2009.
[36] Jens Carsten Jackwerth and Martin Menner. Does the Ross recovery theorem work empirically? Journal of Financial Economics, 137(3):723–739, 2020.
[37] Jean Jacod and Albert N. Shiryaev. Limit Theorems for Stochastic Processes, volume 288 of Grundlehren der mathematischen Wissenschaften. Springer, Berlin, 2nd edition, 2003.
[38] Ying Jin, Zhimei Ren, and Zhengyuan Zhou. Sensitivity analysis under the -sensitivity model: A distributional robustness perspective. Operations Research, 74(2):860–878, 2025. doi: 10.1287/opre.2023.0001.
[39] Jan Kallsen and Paul Krühner. On a Heath–Jarrow–Morton approach for stock options. Finance and Stochastics, 19:583–615, 2015.
[40] Ian Martin. What is the expected return on the market? Quarterly Journal of Economics, 132(1):367–433, 2017. doi: 10.1093/qje/qjw034.
[41] Ariel Neufeld and Julian Sester. On the stability of the martingale optimal transport problem: A set-valued map approach. Statistics and Probability Letters, 176:109131, 2021. doi: 10.1016/j.spl.2021.109131.
[42] Marcel Nutz, Johannes Wiesel, and Long Zhao. Martingale Schrödinger bridges and optimal semistatic portfolios. Finance and Stochastics, 27(1):233–254, 2023. doi: 10.1007/ s00780-022-00490-x.
[43] Jun Pan. The jump-risk premia implicit in options: Evidence from an integrated time-series study. Journal of Financial Economics, 63(1):3–50, 2002.
[44] Dmitry B. Rokhlin. Martingale selection problem and asset pricing in finite discrete time. Electronic Communications in Probability, 12:1–8, 2007. doi: 10.1214/ECP.v12-1240.
[45] Paul R. Rosenbaum. Observational Studies. Springer, New York, 2nd edition, 2002.
[46] Stephen A. Ross. The recovery theorem. Journal of Finance, 70(2):615–648, 2015.
[47] Thomas J. Rothenberg. Identification in parametric models. Econometrica, 39(3):577–591, 1971.
[48] Paul Schneider and Fabio Trojani. (Almost) model-free recovery. Journal of Finance, 74 (1):323–370, 2019. doi: 10.1111/jofi.12737.
[49] Martin Schweizer and Johannes Wissel. Arbitrage-free market models for option prices: The multi-strike case. Finance and Stochastics, 12:469–505, 2008.
[50] Maurice Sion. On general minimax theorems. Pacific Journal of Mathematics, 8:171–176, 1958.
[51] Jeremy Staum. Fundamental theorems of asset pricing for good deal bounds. Mathematical Finance, 14(2):141–161, 2004. doi: 10.1111/j.0960-1627.2004.00186.x.
[52] Zhiqiang Tan. A distributional approach for causal inference using propensity scores. Journal of the American Statistical Association, 101(476):1619–1637, 2006. doi: 10.1198/ 016214506000000023.
[53] Aleš Černý and Stewart D. Hodges. The theory of good-deal pricing in financial markets. In Hélyette Geman, Dilip Madan, Stanley R. Pliska, and Ton Vorst, editors, Mathematical Finance — Bachelier Congress 2000, pages 175–202. Springer, Berlin, 2002.
[54] Qingyuan Zhao, Dylan S. Small, and Bhaswar B. Bhattacharya. Sensitivity analysis for inverse probability weighting estimators via the percentile bootstrap. Journal of the Royal Statistical Society, Series B, 81(4):735–761, 2019. doi: 10.1111/rssb.12327.
How to cite
Shaosai Huang (2026). Linked Physical and Risk-Neutral SPX/VIX Laws: The Identified Set under a Divergence-Bounded Pricing Kernel. Working paper, version of September 2026. Kspectra Research. SSRN 7404180 (doi:10.2139/ssrn.7404180). https://kspectra.ai/papers/linked-spx-vix-laws-identified-set/
@misc{huang2026linked,
  author = {Huang, Shaosai},
  title  = {{Linked Physical and Risk-Neutral SPX/VIX Laws: The Identified Set under a Divergence-Bounded Pricing Kernel}},
  year   = {2026},
  month  = sep,
  note   = {Working paper, version of September 2026},
  doi    = {10.2139/ssrn.7404180},
  url    = {https://kspectra.ai/papers/linked-spx-vix-laws-identified-set/}
}