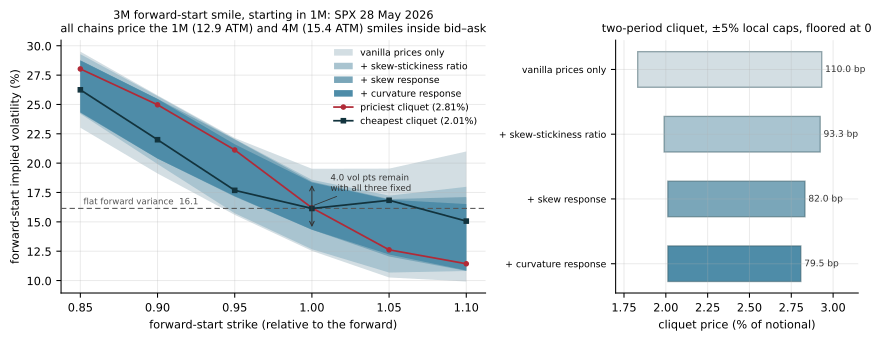
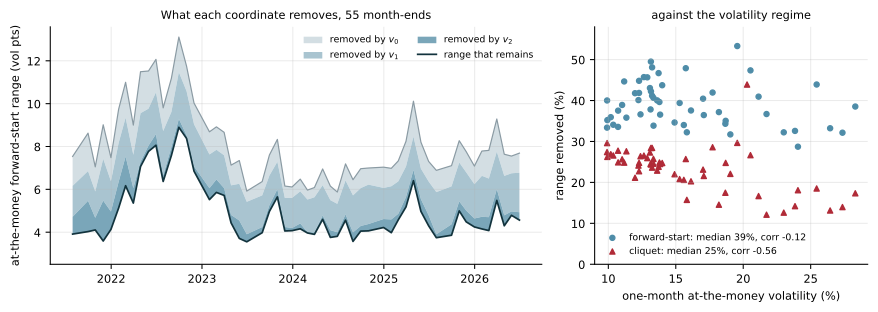
The skew-stickiness ratio and its higher-order extensions measure how the implied-volatility smile responds to moves in the spot. They are what a quoted surface reveals about the martingale kernel generating it, a kernel that is never observed. We ask whether finite Gaussian-mixture martingale chains, whose option prices are finite sums of Black–Scholes prices, can reproduce those dynamics. They can. For stochastic-volatility models with a variance floor and correlation bounded away from , and for local-stochastic-volatility models, under explicit regularity assumptions, we construct exact-martingale finite Gaussian-mixture chains that approximate the marginals and match the finite-step skew-stickiness ratio and its extensions to any prescribed order and accuracy. Part of the contribution is the notion of convergence: the topology generated by the dynamics characteristics themselves, which neither weak nor adapted Wasserstein convergence controls. With components per node and a -dimensional latent state the readout error is up to logarithms, linear in the quantization error, when returns carry a Gaussian component of fixed variance; without one, adapted approximation forces the innovations preceding a price-dependent kernel to vanish, and our bound degrades with the readout order. The limit is the wings: every finite mixture has zero implied-variance wing slopes. Adopting the class therefore costs nothing in at-the-money smile dynamics of any finite order; on an SPX surface, fixing the first three characteristics narrows the at-the-money forward-start range left open by the vanilla quotes from to volatility points, and across fifty-five further monthly surfaces it removes a median of that range.
An arbitrage-free European surface fixes the risk-neutral marginal law of the underlying at each
maturity, but not the martingale kernels joining those laws; kernels with identical marginals
produce different continuation smiles, spot–volatility responses and path-dependent prices.
For independent-increment models the continuation smile is even deterministic in advance,
however well the marginals fit, which is one form of the surface-versus-dynamics problem [19,
Proposition 11.2 and Section 14.3]. The kernel generating those dynamics is never observed. What a
surface does reveal is a hierarchy of at-the-money characteristics — the skew-stickiness ratio
and its higher-order extensions — so a modelling class is adequate only if no admissible
kernel displays dynamics the class cannot express in those coordinates. We ask whether
finite Gaussian-mixture martingale chains meet that test: can they reproduce a prescribed
finite order of at-the-money smile dynamics to arbitrary accuracy while approximating
the marginals and remaining exact asset martingales? They can, at every finite order, for
homogeneous stochastic volatility (SV) and for local stochastic volatility (LSV) (Theorems 7.3
and 9.13).
Why martingale kernels and Gaussian mixtures. The kernel is the natural object for calibrating dynamics: it carries exactly the freedom European
prices leave, lives on the grid of quoted dates, prices every maturity and path-dependent claim from one
law, and combines local and stochastic volatility; as an exact martingale chain it excludes static and
dynamic arbitrage by construction. Finite Gaussian mixtures make such kernels tractable: calls and
their strike derivatives are sums of Black–Scholes terms; martingality is one exponential-barycentre
equation per node, linear in the weights, so price fitting with fixed components is a linear or quadratic
program; positive variances give smooth densities and stable smile derivatives; and chains of mixture
kernels have mixture marginals. Mixtures are an approximation basis, not an economic
mechanism, with a long history in smile fitting [13] and a discrete stochastic-local-volatility
implementation in [29]. The costs are thin tails and component counts that grow with accuracy and
order.
The observable dynamics. What the kernel settles beyond today’s prices is how the smile moves when the spot moves, and
calibrating that motion needs a quantity the quotes show; the skew-stickiness ratio [10, 11] is the one
desks use, and it is the lowest order of a family. Che and Das [18] grade the response of the smile to
spot moves by a transport equation whose at-the-money coefficients extend the ratio to every order; we
take that family in finite-step form, computed from the law of a chain on the grid rather than from a
pathwise derivative. More specifically, on a grid with log price and continuation state , let
be the total implied variance at log-moneyness of the maturity- smile seen from . The
readout consists of at-the-money jets and their projected spot responses over the first step,
where is the order in log-moneyness and the maturity, collected over a finite maturity
set and truncated at an order in . At order zero, and are the level and the skew, and
is the finite-step analogue of that ratio; on the rows determine the transport coefficients of [18] by triangular inversion (Section 2.4). The higher orders are not decoration: the
same study rejects at every tenor from one month to twenty-four, on five years of SPX
surfaces.
The approximation problem. Quantifying over unknown kernels is not possible, so we quantify instead over the classes
practitioners posit. Given a target chain in such a class, an order , a fixed and , the problem is to find
a finite Gaussian-mixture chain with
Density in the topology generated by (1) and the marginals
(Section 2) is the statement that this is always possible; if it is, calibrating in finite mixtures costs
nothing the readout can see.
The difficulty, and the topology that resolves it. Static density of finite Gaussian mixtures is classical [2], and quantizing a Markov kernel yields
weak convergence of finite-dimensional laws; (2) reduces to neither, because its requirements pull
against one another. Exact martingality represents every cell of a finite approximation by its
exponential barycentre, leaving atoms where the readout asks for derivatives of a conditional
density; and a finite chain cannot meet a generic marginal exactly (Proposition 2.5). What
has to be settled first is therefore not how to approximate but what approximation should
mean, and the ready-made answers do not serve. Weak or Wasserstein closeness of path
laws ignores the flow of information, so models close in those topologies can call for very
different hedges; the adapted Wasserstein distance repairs that, makes hedging Lipschitz stable
[3], and controls the conditional laws the rows depend on. It is the natural candidate but
still not enough: finite Gaussian-mixture chains can converge to a Black–Scholes target
adaptedly while their at-the-money smile curvature diverges. No Wasserstein distance on
path laws, adapted or not, makes the readout continuous (Remark 2.4). The notion must
therefore come from the readout itself, together with the marginals, which is what (2) asks for
and what Section 2 constructs: martingality is kept exact, the marginals are allowed to
move, and the readout is required to converge. Placing each demand where it can be met
is the first contribution here, and to our knowledge this topology has not been isolated
before.
Main results. Theorems 7.3 (SV) and 9.13 (LSV) give, for every target in the respective class, one sequence of
exact-martingale finite Gaussian-mixture chains whose errors in (2) tend to zero for every
simultaneously, with the velocity coefficients converging on ; in the topologies of Section 2,
Both
classes assume a compact latent state, Lipschitz kernels with exponential moments, in a compact
subset of and . The SV class adds the Gaussian factor of Assumption 3.1, supplied by a variance
floor with correlation bounded away from (Proposition 3.3), and contains capped Heston
(Proposition 3.4); the LSV class adds one-step return densities with bounded, uniformly continuous
derivatives, of which order uses the first (Remark 9.15). Theorem 8.3 makes the SV statement
quantitative: with components per node and a -dimensional latent state the readout error is up to
logarithms, only that dimension entering the exponent, and the quantization exponent is optimal (Proposition 8.4). An LSV target supplies no factor, so the construction adds Gaussian innovations of
variance . Adapted approximation forces innovations preceding a price-dependent kernel to
vanish (Proposition 9.18), and when that dependence is visible the construction’s adapted
error is of exact order (Proposition 9.19); a final-edge factor may stay (Proposition 9.20).
Two results mark the limits of the class: finite mixtures have zero implied-variance wing
slopes [33], so density fails for a target with a finite moment index once the wing slope
is added to the readout (Proposition 7.4); and with the marginals held fixed rather than
approximated, the finite class caps the dynamics (Proposition 7.5). On an SPX surface, the
vanilla quotes leave the at-the-money forward-start volatility undetermined by points, and
matching the first three readout coordinates as well narrows this to , both ranges exact; over
fifty-five further monthly surfaces the three coordinates remove a median of that range
(Section 10.2).
Method. Both proofs quantize each transition by exponential barycentres and couple target and
approximant bicausally, which carries conditional laws along the sequence. Three obstacles follow. The
martingale-preserving representative is not the optimal one: quantization rates are stated for
centroids, which violate martingality, and martingale-preserving quantization is a problem in its
own right [30], so the estimates are rebuilt around exponential barycentres (Lemmas 4.1
and 8.1). The labels move: the cells chosen at one date create the label set of the next, so the
continuation jets must converge uniformly over sets that change along the sequence, and
errors compound through the recursion (25). And the matched quantity is a jet of implied
variance, recovered by an inversion whose denominator, vega, must stay away from zero along
the sequence (Assumption 6.3). For an LSV target, density derivatives of order converge
once the quantization error vanishes faster than , and a diagonal in serves every order at
once; this is sufficient rather than necessary, since the readout itself needs only at order
(Corollary 9.17).
Scope and related work. The theorems are existence statements about risk-neutral capacity on a finite grid; fixed component
budgets, calibration selection, instantaneous limits and physical-measure use are separate problems
(Section 11). The readout meets two requirements that other gradings fail (Section 2.1): (A) order
zero recovers the skew-stickiness ratio and higher orders refine it; (B) every coordinate is defined from
the grid law, without a Brownian driver or perturbation parameter. Like [18], which confines transport
to compact moneyness intervals and defers the wings to [33], the readout here is at-the-money by
design. Model-side work computes such quantities for given models rather than asking which classes
can match them: a representation formula for the skew-stickiness ratio [24], a second-order
volatility-of-volatility expansion [12], and a quintic Ornstein–Uhlenbeck model tested against the
skew-stickiness term structure [1]. Arbitrage-consistent frameworks for dynamic surfaces characterize
admissible dynamics [34, 35, 16, 17], and [20] derives the motion of the surface inside local
volatility.
Organization. Section 2 defines the readout and the topology it generates, and Section 3 the SV class;
Sections 4–7 prove Theorem 7.3 and Section 9 proves Theorem 9.13. Section 8 adds a convergence
rate and Section 10 the closed-form readout, a cubature bound, two numerical checks of the rates and a
constrained band on an SPX surface; Section 11 discusses scope.
AI-use disclosure. The authors used Anthropic Claude Code and OpenAI Codex as interactive research and writing
tools. They assisted with exploratory discussion, testing and refinement of ideas, literature and source
organization, code development and verification, mathematical error checking, and editorial
revision.
2The jet readout and the topology it generates
Smile dynamics are compared in a finite-step form of the transport coordinates of Che and Das [18],
computed from the law of a chain on the grid, and the topology is the one those coordinates generate.
Static jets are read off conditional smiles by Black–Scholes inversion, dynamic coordinates are
their finite-step projections on the spot increment, and velocity jets follow by triangular
inversion.
2.1The transport construction and what we use
Che and Das [18] write the action of spot moves on total implied variance , with the log-moneyness
and the log forward, as a transport
in which , and are sticky delta, sticky strike and the
skew-stickiness rule. With and , differentiating (3) at the money gives a triangular identity
whose projected form is (7). The family is graded, each being a residual after lower-order
transport.
We use (7) only to define coordinates. As an identity, (3) holds with wherever and degenerates
where ; one trajectory fixes the composite jets , not the dependence of on [18, Remark 5.2]; the jets
are coordinates rather than invariants (Remark 2.2); and they see only the spot-spanned response. We
therefore replace the pathwise by the finite-step projection of Section 2.3 and state the theorems
in the raw coordinates , which remain defined where the are not. The theorems concern
realizability: every projected jet profile generated by a target in the classes of Sections 3 and 9 is
realized to arbitrary accuracy by exact-martingale finite chains. Attainability of an arbitrary
empirical jet vector is not claimed, nor a characterization of the transport flows compatible
with martingale dynamics. Other gradings fail requirement (A) or (B) of the introduction:
Bergomi–Guyon functionals [12], Wiener-chaos order and martingale-expansion coefficients [23] need a
forward-variance representation or a perturbation parameter, so they are not computable from the grid
law of a finite mixture; marginal moments and cumulants are not nested descriptors of the at-the-money spot response; and the number of time points [27] is a complementary
axis.
2.2Conditional smiles and static jets
For any chain considered below, let denote a sufficient continuation state: a state variable that
determines the conditional law of normalized future returns. For and a state value , define
Here and below the expectation denotes the Markov continuation started from , fixing
one continuation version on the state space. Let denote the normalized Black–Scholes call
with log-strike and total variance ,
The conditional implied total variance solves
and its
ATM jets are
For the homogeneous SV class of Section 3, , the latent state; for a local-SV
target, ; for the lifted approximants of Section 9, , the finite proxy label on which their
normalized continuation law depends. Quantities of the th approximant carry a subscript , as in
.
Lemma 2.1 (Finite-dimensional static jet map).Fix and suppose near zero. On any set where
the ATM solution stays in a compact subset of , the vector is a continuous function of the
call derivatives . The only implicit-function denominator is the Black–Scholes vega . If , then is
smooth near zero.
Proof.Set . For , strict monotonicity of gives continuity of the scalar inverse at the money. For , since ,
the implicit-function theorem gives a local solution (and a smooth one when is smooth). The first
derivatives are
Repeated differentiation gives the same structure at every finite order: the numerator is a
polynomial in lower jets and derivatives of , divided by . On the stated compact set these operations are
continuous.∎
2.3Finite-step projection
Fix the observation edge and an option maturity with . At the known root define
On the domain ,
the projected spot derivative of the th smile jet is
Since and refer to the same maturity one step
apart, the deterministic part of the calendar decay drops out of the covariance, leaving a spot response.
The denominator is positive: under Assumption 3.1, and for LSV targets and their proxy
approximants see (45) and Lemma 9.12.
In regression terms, is the population OLS slope of on , with residual vanishing exactly when is
affine in . For a Gaussian-mixture edge with component label , and , one has with , and if on ; if
varies within components, the law of total covariance adds .
2.4Triangular inversion and the pivot
The projected velocity jets are defined algebraically by
This is the pattern obtained by differentiating
(3) at the money, with in place of the pathwise ; identifying the two would require the instantaneous
limit of Section 11.
If , the system is triangular:
More generally, if the hierarchy is compatible and , the rows impose
and, for ,
so need for and for , and near that stratum (9) is a continuous -pivoted extension
wherever . Approximation may perturb the vanishing jets, so the theorems use raw coordinates globally
and velocity coefficients on the regular chart .
For finite and , the raw readout collects , , and , , over , as in (1). It recovers on the chart , where
the velocity coefficients are continuous functions of finitely many raw coordinates, so adjoining them
leaves the topology unchanged; raw convergence also gives convergence of any fixed -pivoted extension
at a target with .
Remark 2.2 (Transformation law: the velocity jets are chart coordinates). The are jets of a
vector field and transform as such. They are invariant under a change of variance level , which is
why they compare across volatility levels. Under a linear change of moneyness , , so scales like
, is invariant and scales like ; under with , and . They are therefore coordinates relative to
a parametrization: under the linear subgroup the invariants are the monomials of total weight
zero, such as and , and quoting the smile in divides by . We fix ; the raw coordinates carry
no convention beyond this choice.
2.5The topology generated by the readout
Let be a class of rooted marked martingale chains. For maps , is the initial topology, the coarsest
making every continuous; a sequence converges in it exactly when every coordinate does. The
construction is textbook, and the content is the choice of maps. Generated by the readout, the
topology adapts to the quantities that describe the dynamics: two chains are close when their
at-the-money jets and projected spot responses are close, whatever kernels produce them.
Adjoining a coordinate refines the topology and can destroy density, as the wing slope does
(Proposition 7.4). denotes the laws on a metric space with finite th moment, with the distance
.
Lemma 2.3 (Image density).Let carry the product topology and let . For ,
Proof.The sets , with product-open, form a base of the initial topology. Such a set is nonempty
exactly when meets , and it meets exactly when meets . This is precisely image density in the
subspace .∎
For an ambient class on which the raw readout is defined, let and , and, for finite and , define
The full moving-marginal topology is generated jointly by all , so a basic neighbourhood
constrains finitely many coordinates; target and approximant may have different mark spaces,
since every generator is a model-level map. The topology is generated by the pseudometric
so lies in the -closure of a class exactly when its finite-order calibration error vanishes; exact
martingality constrains the candidates rather than entering the error. For an approximating class and
a target , write
Thus means zero calibration error at every finite order and maturity set; both
constructions below achieve it with a single sequence.
Density is proved along one constructed sequence, by showing that every generator converges and
applying Lemma 2.3; adapted Wasserstein convergence (Section 5) is a step of that proof, not a finer
topology.
Remark 2.4 (The readout is not weakly continuous). No Wasserstein distance on path laws,
adapted or not, makes the readout continuous on the classes below. Take a two-step Black–Scholes
target, independent with , and let with . On each edge write and keep the second factor, but
quantize the first by exponential barycentres on cells of width of order , placing one cell on each
edge so that the two barycentres sum to ; a barycentre moves continuously as its cell slides.
The result is a finite chain as in Definition 5.1 with edge variances , and coupling the quantized
factors optimally and the Gaussian factors identically gives . The two placed cells carry masses of
order , and the component through both is , centred at the money, so the density of is at least of
order there. With the call function of , while and converge, so the expression for in the proof
of Lemma 2.1 diverges: the root curvature jet at does not converge. What restores continuity
in Section 6 is a Gaussian factor whose variance is held fixed along the sequence. Section 9 lets
that variance vanish too, but only with the quantization error driven to zero faster than a power
of it; here the variance vanishes faster than the quantization error.
2.6Moving marginals and exact martingality
For the discounted asset and (so the log forward is ), martingality is the exponential barycentre
identity
for every state reached by the chain.
Proposition 2.5 (Marginal rigidity).Let start from a known root and carry a label taking finitely
many values at each date, with transitions
so that the component index and the successor label depend
on the current label alone. Then for every ,
for a finitely supported , which is determined by and . In
particular a law on is the date-marginal of such a chain only if it is the convolution of a finitely
supported law with a centred Gaussian.
Proof.The label chain evolves independently of the Gaussian increments. Conditionally on the
finitely many label and component paths up to date , is plus the chosen locations, less , plus
independent centred Gaussians, hence Gaussian with variance ; mixing over the finitely many
paths gives (12). The Fourier transform of does not vanish, so , and with it , is determined.∎
Both finite classes below have this form, with the factor variances (Definition 5.1) or
(Definition 9.6, Lemma 9.7). Under Assumption 3.1, with and the sum of the target’s factor
variances, and matching (12) is impossible if , forces to be finitely supported if , and forces it to
be a finite Gaussian location mixture with a common variance if . For generic targets the
marginals can therefore be approximated — in by Theorems 7.3 and 9.13, and in total
variation, since the densities converge uniformly (Lemmas 6.2 and 9.10) — but not attained.
This is why the formulation lets the marginals move; holding them fixed would in addition
cap the dynamics (Proposition 7.5). The approximants below satisfy (11) exactly, so their
spot laws are in convex order. A nondegenerate time-zero law with can be included by
quantizing with Lemma 4.1, shifting back and adding an independent , , which keeps
exact.
3Model class and Gaussian factorization
A variance floor with imperfect correlation leaves a Brownian direction unspanned by the volatility, so
each transition splits into a residual return carrying the whole exponential barycentre and an
independent mean-one Gaussian factor. This restriction on the target is checkable from the model’s
coefficients (Proposition 3.3); the factor keeps martingality exact under quantization, supplies the
smoothing of Section 6 and yields the rate of Section 8. Section 9 drops it and pays for
it.
Fix dates containing the observation step and all maturities, a compact convex , and states with
known root , where is the latent volatility state. With , homogeneity means that for kernels ,
For put , so that for .
Assumption 3.1 (Independent mean-one Gaussian factor). For every edge , there are and a kernel
such that, jointly over the whole grid,
where the are mutually independent and
Moreover,
By (14) and , (11) holds exactly. Fix and the metric on .
Assumption 3.2 (Kernel regularity and moments). There are and such that for every and ,
Proposition 3.3 (Stochastic volatility supplies the factor).Suppose
where is independent of , is a true martingale from every initial state under consideration, is a
well-posed strong Markov solution adapted to the augmented filtration of , and
Then, after passing to
an extension of the probability space carrying the auxiliary normals constructed in the proof, the chain
satisfies Assumption 3.1with, for any fixed ,
Proof.Let (augmented by the initial state), and condition first on . On the log return is conditionally
Gaussian,
where
On an extension of the probability space, do this simultaneously on every disjoint grid edge using
mutually independent pairs of standard normals , independent of the -driven path, and set
Conditionally on , has law , independently across edges, as do the original increments,
whose -parts live on disjoint edges; so leaves the law of the grid chain unchanged. The
vector is independent of and , which gives the path-level independence in Assumption 3.1,
and is a function of , the -increments on and , all but independent of , so its law given
is a kernel . Finally, homogeneity and the asset-martingale property give
Proposition 3.4 (A floored and capped square-root model lies in the class).Fix , put , and let be
bounded and Lipschitz with
Let , let be independent of , let , and consider
Then takes values in , and
the grid skeleton of (20) satisfies Assumptions 3.1, 3.2and 6.3; hence it lies in and Theorem 7.3applies to it. With and equal to and away from the endpoints this is floored and capped Heston; if ,
only needs modifying.
Proof.Replacing by , which agrees with it on , makes the system globally Lipschitz, so it has a
unique strong solution. The coefficient and the drift both vanish at , so the constant solves the
equation with that drift, and comparison for one-dimensional equations with a common Lipschitz
diffusion coefficient [31, Section 5.2.C] gives from every start in ; the drift gives in the same
way. Hence is invariant, endpoints included.
Assumption 3.1. On one has , so the volatility is bounded and floored, and . Boundedness of
gives Novikov’s condition, so is a true martingale from every state, and is a well-posed strong
Markov solution adapted to the augmented filtration of . Proposition 3.3 therefore applies and
yields (13) with for any .
Assumption 3.2. In the representation of Proposition 3.3, couple the copies started from
and through the same and the same auxiliary normals. Then , the square root is Lipschitz
because , and Gronwall with the Burkholder–Davis–Gundy inequality bounds , hence , and the
marks, by a multiple of in ; this is (15). For (16), condition on the path of : the residual return
is Gaussian with variance at most and mean bounded by plus a stochastic integral of quadratic
variation at most . Both terms are sub-Gaussian with parameters depending only on and the
mesh, so every exponential moment is finite uniformly in the starting mark; in particular (16)
holds for any .
Assumption 6.3. The volatility satisfies pathwise, and a European call is a convex payoff, so
by the comparison theorem for misspecified volatility [21] the conditional call price lies between
the Black–Scholes prices at those two volatilities. Monotonicity of then places the ATM implied
total variance in , a compact subset of independent of the mark.∎
4Log-barycentric quantization
Quantization theory [25] gives rates for the unconstrained problem; the point here is that representing
cells by exponential barycentres preserves martingality exactly at every level.
Lemma 4.1 (Exact exponential-barycentre quantization).Let have unit exponential mean, ,
and a finite exponential moment for some . Then there are finitely supported laws such that
Proof.Let . Since is standard Borel, choose increasing finite sigma-fields whose union generates
. Set
The convexity of gives , and finiteness of makes finitely valued. Moreover,
Martingale
convergence yields and , hence , almost surely. Conditional Jensen for the convex maps and
gives
Since , integration gives the asserted uniform two-sided exponential bound. Therefore is
uniformly integrable. Since is compact, in every . Thus in , which implies . Taking proves the
result.∎
The partitions must generate , not : if the cells are unions of full -fibres, per-fibre normalization
gives every the value , leaving no spot–mark covariance.
5Finite marked trees and adapted convergence
Quantizing every node gives a finite marked tree of exact martingale kernels, and a recursive bicausal
coupling gives adapted convergence.
For path laws on define
where denotes the bicausal couplings [3, 5]. For Markov chains on the
grid, recursively coupling next-step kernels as functions of the two current states gives such a
coupling.
Definition 5.1 (Finite marked GM chain). A finite marked GM chain has finite continuation-label
sets and edgewise constants , all part of the chain’s data. The label space may be the target latent
space, as in the homogeneous construction, or may include a finite proxy log-price, as in Section 9.
From , , its transition is
where
Every kernel (22) is an exact asset-martingale kernel:
Theorem 5.2 (Finite-tree approximation).Under Assumptions 3.1and 3.2, there are finite marked
GM chains starting from such that
every transition is an exact asset-martingale transition;
;
for every , is a finite Gaussian mixture, and converges to in .
Proof.Fix and put . Suppose the finite set has been constructed. For every , apply Lemma 4.1
to and choose with and exact exponential barycentre. The conditional-Jensen estimates in
that lemma and (16) give the same uniform -exponential bound over all selected nodes and all
. Let be the union of the finitely many successor marks. This recursively defines (22); exact
martingality was checked above.
We construct a bicausal coupling recursively. Given current states and , first note that, by (15),
Choose a Borel measurable -optimal coupling kernel for this pair of laws; such measurable selections
exist for Wasserstein costs on Polish spaces [36, Corollary 5.22]. Its conditional cost is bounded by the
right side of (24) plus , hence by . Use the same independent in the two transitions. If the
coupled residual variables are and , then
Writing for the date- coupling cost in the metric
of (21), the price gap carries over and the coupled residual–mark cost adds at most , so
Minkowski’s inequality gives
Iterating over the finite grid gives an bound at every date. The
selected coupling kernel at each step depends only on the pair of current states, and the
common is drawn independently of the coupled residuals, so each coordinate receives its
own transition kernel; the coupling is therefore bicausal. This proves and the marginal
convergence.
It remains to identify the approximating marginal. Conditional on a finite residual branch path up
to date ,
There are only finitely many branch paths, so is a finite Gaussian mixture.∎
Since with common mean , the finite-lognormal-mixture spot laws converge in , and so do the call
prices on and , uniformly in strike:
6Continuation stability and Gaussian smoothing
The recursive coupling controls future conditional laws, and the Gaussian factor on the
last edge before each maturity upgrades this to uniform convergence of densities and their
derivatives.
Lemma 6.1 (Future conditional laws).Fix . Let and suppose . Couple the target chain started
from at and the approximating continuation started from , with the same normalized current
log price, by the construction in Theorem 5.2. Then their future path laws through converge in
. Moreover, with
and the analogous , one has
Proof.The initial state error is . At each later edge, the measurable coupling estimate following
(24) applies with the same constants. The finite-horizon induction used in Theorem 5.2 therefore
bounds the future path error by , which tends to zero. The coupling is again bicausal. On its
extended space every is coupled identically and every is controlled by the corresponding edge
estimate. Minkowski’s inequality applied directly to the displayed residual sums gives the stated
bound.∎
Lemma 6.2 (Common-Gaussian smoothing).Let with , and fix . If and , where is the density of ,
then for every ,
Proof.Take a coupling attaining, or arbitrarily approaching, . For every , the mean value theorem
gives
Take expectations and then the supremum over .∎
Since with independent and additive at maturity, the conditional return law is the residual law
convolved with , and Lemma 6.2 applies.
Assumption 6.3 (Implied-variance nondegeneracy). For every date pair under consideration,
the target ATM implied total variances stay in one compact subset of uniformly over .
Lemma 6.4 (Static jets from converging return densities).Fix , and an order . For each let be a
set of labels and, for , let and be coupled log returns with unit exponential mean. Suppose
that
;
;
and have densities and of class such that, for every , and ;
the ATM implied total variances of the lie in one compact subset of .
Then, writing for the th ATM jet of the implied total variance of ,
Proof.Write for the two call functions. By and Hölder’s inequality, (1) and (2) give . Next,
, and for every , ; letting and then gives uniform convergence of . Since , each with is a
fixed linear combination of and the values , , so (3) gives uniform convergence of all of them,
and the vectors stay in a bounded set. By (4) and the convergence of , the approximating ATM
variances lie in a slightly enlarged compact subset of for large , on which the map of Lemma 2.1
is uniformly continuous on bounded sets.∎
Proposition 6.5 (Convergence of conditional static jets).Under Assumptions 3.1, 3.2, and6.3, for every , every finite ,
The target map is continuous on . Consequently, if and , then .
Proof.Apply Lemma 6.4 with , with the coupled normalized returns started from , and
with every ; all conditional forwards equal one exactly. Hypothesis (1) is Lemma 6.1 with both
continuations started from the same label : the residual sums are then within in , with a constant
independent of , and the Gaussian factors are coupled identically. For (2), the bound follows edge
by edge from the tower property: conditioning on and using uniformly in , valid since , gives a
factor per edge and hence over the finite grid, uniformly in ; the independent Gaussian factors
contribute , and the atomic kernels inherit the bound by Lemma 4.1. For (3), both returns
are residual laws convolved with , so and Lemma 6.2 gives the convergence at every order.
Hypothesis (4) is Assumption 6.3. Applying the same lemma to target continuations started
from and coupled through (15) gives continuity of the target jet map; the sequential claim follows
by the triangle inequality.∎
7Projected dynamics and the density theorem
The first-edge factorization reduces both projections to covariance ratios over the residual
kernel.
Homogeneity makes the continuation jet a function
of the successor mark. Consequently and , so
For the finite chain write its first-edge atoms as with weights , and put
Then
Lemma 7.1 (Projected rows from converging continuation jets).Let and be coupled first-edge
log returns and successor labels, taking values in a finite set and in a metric label space, with
and in for some . Let on and on the label space be bounded uniformly in , with uniformly
continuous and . If , then
Proof.Since , and the second term tends to zero in probability by uniform continuity, in
probability, and the uniform bound upgrades this to . Hölder’s inequality against in gives
convergence of and of the means, and gives .∎
Lemma 7.2 (Projected readout continuity).For every finite and every ,
Proof.Apply Lemma 7.1 under the first-edge coupling of Theorem 5.2, with , , , , and .
Proposition 6.5 supplies the hypotheses on and : continuity on the compact is uniform and
bounds , and uniform convergence then bounds the uniformly in . Finally . The two sides are
(29) and (28).∎
Let be the class of homogeneous rooted targets on the fixed grid and state space that satisfy
Assumptions 3.1, 3.2, and 6.3. Let be the finite marked GM chains of Definition 5.1 whose finite labels
lie in the homogeneous mark space , with the stated log and spot moments and well-defined raw
readouts, and set
Theorem 7.3 (Homogeneous-SV density at every finite projected order).Let and let be finite. Then
the finite marked GM chains of Theorem 5.2satisfy:
every is an exact asset martingale;
for every , the log-price marginal is a finite Gaussian mixture and converges to in , while the corresponding finite lognormal spot marginal converges in ; the marginal remains the fixed root ;
for every finite and every , the static jets through and the projected rows through converge;
for every finite and each with the regular pivot ,
Consequently
and is dense in both for the raw-readout topology and for . Equivalently,
Proof.Items 1 and 2 are Theorem 5.2 and the paragraph following its proof. Proposition 6.5
with , whose only label is the root mark, gives all finite static jets, and Lemma 7.2 gives all finite projected rows. The standard inversion (8) is a continuous triangular rational map near
a target with , so the velocity jets converge. The sequence does not depend on or , and every
finite collection of raw readout coordinates converges along it, so Lemma 2.3 gives density in the
initial topology. The marginal convergence in item 2 gives density in .∎
Proposition 7.4 (The density does not extend to the wings).For a chain and a maturity let
be the right-wing slope of the root smile, and the right moment index. If is a finite Gaussian
mixture — in particular for every chain in or — then . If , then
Consequently, once is adjoined
to the readout, no target with a finite right moment index lies in the closure of either finite class;
the left wing and the left moment index behave alike.
Proof.A finite Gaussian mixture has exponential moments of every order, so , and Lee’s moment
formula [33] gives . For the same formula gives the displayed value, which is positive because for
every finite . The set is then a neighbourhood of in the augmented initial topology containing
no chain of either class, the finite-mixture property of their marginals being Proposition 2.5.∎
Proposition 7.5 (Fixed marginals cap the dynamics).Let be a chain as in Proposition 2.5whose
date-return marginal is
Then its first edge has variance , its first-edge locations take the value with
probability , and every projected row is
where is the average of the continuation jet over the first-edge
branches located at . In particular, if , every chain in either finite class whose first marginal is Gaussian
has for all and .
Proof.By Proposition 2.5, with finitely supported and the first-edge variance, while . If , then
is a Gaussian convolution, which is never finitely supported. If , then , which is unbounded,
unlike a characteristic function, because the almost periodic sum returns arbitrarily close to its
value at the origin. Hence , and uniqueness gives . Writing for the first-edge location, with
independent of the label chain, so the numerator of (6) is ; grouping the branches by location,
and using , gives (30), the denominator being . If , is constant.∎
Remark 7.6 (How much the cap binds). A general martingale chain with the same two
marginals is not capped, since its continuation may depend on where falls inside a component.
With lognormal marginals at the SPX one- and four-month at-the-money volatilities of
Section 10.2 (), every finite chain has , while martingale couplings of grid discretizations of the
same marginals reach , stably under refinement. At the resolution of the SPX fit () the cap is
mild but strict: since the readout averages jets after the convex at-the-money inversion, branches
sharing a location can move it, and a piecewise-linear relaxation over such branches certifies for
the whole finite class, attained to within , against for grid couplings. Both contain the value ()
of [18]. Refining the atoms is thus what lets the finite class express dynamics, and the bands of
Section 10.2 are computed inside the capped set.
8A convergence rate
Theorem 7.3 produces a sequence, not a budget. Under the same assumptions the construction admits
an explicit rate in the number of atoms per node, linear in the quantization error rather than
square-root: the exponential barycentre is exact at every resolution, so no accuracy is spent restoring
martingality, and the fixed-variance factor makes the readout a Lipschitz functional of the
residual law. Throughout, has diameter , is the constant in (15), and are those of (16), and
.
Lemma 8.1 (Quantization at a rate).Let be as in Lemma 4.1, with . For every there is a finitely supported with , with at most
atoms, with exact barycentre and two-sided exponential bound , such
that
Equivalently, in terms of the atom count,
Proof.Let and put , so that . Partition into intervals of length at most covering and the
two tails , , and into at most sets of diameter at most ; the cells are all products of the two
partitions, tails included, and number at most (31). On a cell with set and . The map on is
a coupling of with ; the tower property gives the exact barycentre and the conditional Jensen
estimates of Lemma 4.1 give the exponential bound.
For the cost, is monotone, so lies between the essential infimum and supremum of on ; hence on
every core cell, and on every cell, contributing at most . On a tail cell, write . From for ,
On the lower
tail, Jensen gives while , so . On the upper tail, Hölder gives , hence ; the map is increasing on and ,
so . Since , both tail terms are . Taking -th roots gives (32). Finally, choosing in (31) and substituting
into (32) gives (33).∎
The second ingredient replaces the splitting at a scale in the proof of Lemma 6.4, which would cost
a square root if optimized: with the factor present, the ATM tail probability is the expectation of a
Lipschitz function of the residual.
Lemma 8.2 (Linear readout response).Fix and let and with independent of and . Write and , and let be the cost of a coupling of and , . If with , then
with absolute.
Proof.The level bound is and Hölder, as in Lemma 6.4. For , , so
because . The map is Lipschitz
with constant , so the difference of the two expectations is at most . For , the identity expresses
through and the values , , where is the density of ; the same holds for . Each return density is a
residual law convolved with , so Lemma 6.2 gives ; with the of the largest power is , attained at when
.∎
Theorem 8.3 (Rate for the homogeneous class).Let , let be finite and finite. For let be the finite
marked GM chain of Theorem 5.2built from Lemma 8.1with at most atoms per node. Then every is
an exact asset martingale, is a Gaussian mixture of at most components, and
where
On a chart
with the velocity jets satisfy the same bound, with a constant depending in addition on
.
Proof.Apply Lemma 8.1 at every selected node with the common budget , giving a per-edge
error as in (33). The coupling recursion (25) gives , and when ; the same recursion started
from a common label bounds the continuation residuals of Lemma 6.1 by , uniformly over labels.
The order- readout needs only for , through , and Lemma 8.2 converts this into , uniformly
over reachable states, the exponential moments being uniform by the tower-property estimate in
Proposition 6.5. By Assumption 6.3 the target’s ATM variances lie in a compact subset of . The
approximants’ are at least , by Jensen’s inequality in the independent factor, and bounded above
through the exponential moments, so for every all of them lie in one compact window, on which
the jet map of Lemma 2.1 is with denominator bounded away from zero; it is therefore Lipschitz
in the call-derivative vector, which gives (36) for the static jets. For the rows, the quantization
coupling is explicit, so is bounded by the uniform level error plus through the Lipschitz label
dependence of Lemma 6.1; Hölder against and then give the same bound for through (29). The
triangular inversion (8) is smooth near a target with , which transfers the rate to the velocity
jets.∎
Proposition 8.4 (Lower bounds).Fix and use on the metric .
If has a density bounded below by on a cube of side , then every law with at most atoms satisfies , with .
If has a density bounded below by on a cube of side in , then every chain whose date-mark takes at most values satisfies
Proof.Both parts are one volume argument in dimension , respectively . Balls of radius about
the atoms cover at most half of the cube when , where is the volume of the unit ball; the
uncovered half carries mass at least at distance at least from every atom, and every coupling
must move that mass onto the atoms, so . Take . For (2), the adapted distance dominates the
Wasserstein distance of the date- marginals, and the mark marginal of has at most atoms.∎
Remark 8.5 (What the rate does and does not say). By Proposition 8.4(1) the quantization
exponent is optimal up to the logarithm, so exact martingality costs nothing in it. When the
date- mark law has a density bounded below on a cube, part (2), the recursion (25) and (33)
give
the lower bound holding for every finite chain, martingale or not; the exponents differ by
one because the return coordinate is smoothed rather than quantized, and whether a fixed factor
closes the gap is open. Neither bound concerns the readout alone: Proposition 10.1 matches the
order- readout of one edge exactly with at most components, so a readout lower bound would
have to come from the multi-step recursion, and we have none. The constant of Theorem 8.3
degrades like , so a high-order readout needs a factor that is not small relative to the residual
scale, and the bound is per node, the date- marginal having up to components.
9Local stochastic volatility
Local volatility rests on mimicking [28, 15]; the targets here are grid skeletons of local-stochastic-volatility
models, whose return kernel depends on the log price and which supply no Gaussian factor. A finite proxy log price records where the local kernel is sampled, while the traded log price receives
independent mean-one Gaussian innovations of vanishing variance; the class contains the homogeneous
one (Remark 9.14).
9.1Local-SV kernels and readout regularity
A motivating diffusion is
with as in (18), , , and independent of . Conditioning on the -path now
leaves a state-dependent diffusion, so the argument of Proposition 3.3 does not apply, and we work
directly with grid kernels.
Put with , and for let .
Assumption 9.1 (Local-SV Markov kernels). Fix and . The state space is compact and convex, the
root is known, and is a time-inhomogeneous Markov chain with kernels . There are such that, for
every and ,
Assumption 9.2 (All-order terminal-kernel regularity). For every , the return marginal has a density
For each integer , is bounded and uniformly continuous on . Equivalently, for suitable constants and
moduli as ,
Assumption 9.3 (Local-SV readout window). For every date pair used by the readout, the target
ATM implied total variance satisfies
and
For (37), bounded volatility gives the exponential moments and Lipschitz coefficients give (39);
Assumption 9.2 holds for the following class.
Proposition 9.4 (A class satisfying Assumptions 9.1–9.3).Fix , let be a Brownian motion
independent of , and write for . Consider the local-SV model with an independent variance floor and
edge-frozen leverage,
with as in (18) and valued in a compact convex (for instance by the boundary
conditions of Proposition 3.4), and bounded and globally Lipschitz with . Then the grid chain is
Markov and satisfies Assumptions 9.1, 9.2and 9.3, with and
where is any constant realizing the
synchronous-coupling estimate (39).
Proof.On each edge the leverage reads the frozen spot and the -driven mark path, so from the current
state the increment splits as with
With the leverage frozen at , depends on and the increments on the edge, and on the increment
only. Post- increments of and of are independent of each other and of , so given the state and
which
gives (42). For the modulus, the mean value theorem bounds the -increment by , and Lemma 6.2 gives
Driving copies from by the same makes the equal, and Gronwall, with Lipschitz because , bounds the
distance of the return–mark pairs by a multiple of ; this gives (39) and, adding the two moduli, (43).
Since is bounded, Novikov’s condition gives , so independence gives (38), and bounded coefficients give
(40).
For Assumption 9.3, with the instantaneous variance lies in ; since a call is convex, [21] places the
conditional call price between the Black–Scholes prices at these volatilities, and monotonicity of places
the ATM total variance in , and .∎
Remark 9.5 (Why the leverage is frozen). Read continuously, depends on the past of within
the edge, so and need not be independent and the convolution identity is lost; Lipschitz
coefficients alone need not give bounded density derivatives of every order. The alternative is
parabolic: smooth coefficients and a uniformly elliptic diffusion matrix for give Assumption 9.2
by [22, 32], but a chain invariant on a compact mark space degenerates at , so we rely on
Proposition 9.4 or on Assumption 9.2 directly.
For the LSV target the smiles, jets and rows are those of Section 2 with : , , , and is the covariance
ratio (6).
9.2Finite proxy-GM chains
Definition 9.6 (Finite proxy-GM chain). At date let be finite and write a proxy label as . At each
choose positive weights and successor data
such that
The successor label is
For an edge variance , the
transition from the full approximating state is
The root is . The proxy coordinate is part of the finite continuation label; the traded log price is .
Let be the natural filtration of .
The normalized future return law depends only on the label , so the approximating smiles and jets are
written and . Equivalently, after choosing branch at , draw , independently of the complete
proxy-label chain and of the other Gaussian innovations, and set
Lemma 9.7 (Exact martingality and finite marginals).Every finite proxy-GM chain is an
exact asset martingale. Put , with the convention . Then
independently of . Consequently
Thus every positive-date log-price marginal is a finite Gaussian mixture, with at most components.
Proof.Conditioning on the current state and using (47),
Subtracting the proxy recursion from
the traded-price recursion in (49) gives (50). By the independent product construction in (49),
the complete proxy-label chain is independent of . Conditioning on the finitely many proxy labels
gives (51).∎
9.3Diagonal quantization and lifted adapted convergence
Let denote the density of .
Lemma 9.8 (Diagonal martingale smoothing).Let , , be probability laws whose derivatives through
order are bounded and uniformly continuous jointly in , and suppose . Let be finite and let
Moreover , and the common
modulus of continuity gives
The limit follows by bounded convergence, the modulus being
bounded. Combining the two bounds proves (53). Since denotes variance, ; thus is a sufficient
explicit rate.∎
Equip the lifted state space with the metric , and use it in the corresponding adapted Wasserstein
distance.
Theorem 9.9 (Lifted finite-tree approximation).Under Assumptions 9.1and 9.2, there are integers ,
variances , and finite proxy-GM chains with on every edge such that:
every transition is an exact asset-martingale finite-GM transition and every , , is a finite Gaussian mixture;
after lifting the target and approximating states to the common space
Proof.Choose any . By Assumption 9.2 and the approximate-identity estimate in Lemma 9.8, one may
choose with
Put and choose .
Start with . Suppose is finite. For every , apply Lemma 4.1 to the full joint law . Choose
with and
exact exponential barycentre (47). The conditional-Jensen estimate in Lemma 4.1 gives
the uniform -exponential bound for the selected return atoms. Define as the finite set of
successor labels . Recursion gives one coherent chain over the entire grid, including all option
maturities.
Since and projection onto the return is -Lipschitz, the return marginal of (57) is within in of
. Equations (56) and the definition of therefore give (54) through the two estimates in
the proof of Lemma 9.8, used directly because the order grows: the quantization term is
by the choice of , and the approximate-identity term is at most by (56), both already
uniform in , in , and in the node. Exact martingality and finite-GM marginals follow from
Lemma 9.7.
It remains to prove the adapted convergence. Given a current target state and proxy label , the
triangle inequality and (39) give
Choose a Borel measurable -optimal coupling kernel, which exists by
measurable selection of optimal plans [36, Corollary 5.22], the map being continuous into
by (39). Denote the coupled target return–mark by and the proxy atom by . Set
and
independently add to obtain as in (49). The joint one-step kernel has first marginal and second
marginal , each depending only on its own current state. Recursion therefore gives a bicausal
coupling.
With , the argument of Theorem 5.2 with (58) in place of (24) gives the recursion (25) from ,
the roots coinciding, hence . By (50),
For the lifted-state distance,
Summing over the
finite grid gives the quantitative bound
and hence adapted convergence. Projection by is
-Lipschitz for , which proves (55). In particular in law, so ; both have first moment , by exact
martingality, and for nonnegative laws weak convergence with converging first moments is
convergence.∎
Since normalized proxy returns depend only on the label, the same recursion can be started from
any with both log prices normalized to ; it gives for the coupled continuations and the uniform bound
9.4Continuation densities and smile jets
Fix . Under the target continuation from , write and . Conditioning at gives the density
For the proxy
continuation from , normalize the traded starting log price to and write . Its terminal density is
Lemma 9.10 (Terminal-kernel transfer).For each fixed and ,
For each , is bounded and uniformly
continuous.
Proof.For large , ; couple the preterminal continuations by (60). Differentiation under the
expectation is justified by dominated convergence, with the bounds of (42) and, for large , for
by (54). Add and subtract . The first difference is bounded uniformly by (54). With , the second
is bounded, uniformly in , by . Choose the modulus bounded by . For every ,
The second term
tends to zero by (60); letting proves (63). The same calculation for two target continuations, via
(39), gives the uniform continuity.∎
Proposition 9.11 (Local-SV conditional static jets).Under Assumptions 9.1–9.3, for every and
every fixed ,
The target map is bounded and uniformly continuous on .
Proof.Apply Lemma 6.4 with and the coupled normalized continuation returns. Hypothesis (1)
is (60); (2) follows from (40) by the edgewise tower argument in the proof of Proposition 6.5,
the Gaussian innovations contributing a factor bounded uniformly in and the atomic kernels
inheriting the bound by Lemma 4.1; (3) is Lemma 9.10, the target bounds coming from (61) and
(42); and (4) is Assumption 9.3. The same lemma applied to two target continuations coupled
through (39), with the uniform continuity of Lemma 9.10, gives a common modulus for the jets,
hence bounded and uniformly continuous .∎
Lemma 9.12 (Local-SV projected rows).For every fixed and ,
Proof.Apply Lemma 7.1 under the first-edge coupling of Theorem 9.9, with , , and . The
coupling gives in , and in because the proxy gap (50) vanishes with . Proposition 9.11 supplies
the jets, bounded and uniformly continuous, and their uniform convergence bounds the uniformly
in ; (45) gives the variance.∎
9.5The second density theorem
Let be the rooted Markov chains on the grid, with state space and known root, whose kernels satisfy
Assumptions 9.1–9.3, such as the chains of Proposition 9.4. Let be the finite proxy-GM
chains of Definition 9.6 with the stated moments and well-defined raw readouts, and put
Theorem 9.13 (Local-SV density at every finite projected order).Let and let be finite. The
single diagonal sequence of Theorem 9.9satisfies items 1–4 of Theorem 7.3, with in place of .
Consequently
Proof.Items 1 and 2 are Theorem 9.9 and Lemma 9.7. Lemma 9.10 and Proposition 9.11 give
every fixed finite collection of root and continuation static jets, the root jets being the case ,
whose only label is the root; the diagonal makes one sequence sufficient for all finite orders.
Lemma 9.12 gives the projected rows. On the regular chart, the triangular map (8) is continuous,
which gives the velocity jets. Raw-coordinate and marginal convergence is convergence in every
generator of (10), so in ; as was arbitrary, the class inclusion follows.∎
Remark 9.14 (Relation to the homogeneous theorem). The hypotheses of Theorem 7.3 imply
those of Theorem 9.13: under Assumption 3.1 the return density is , so and, by Lemma 6.2 and
(15),
which is Assumption 9.2; the remaining conditions transfer by independence of , and . The
inclusion is strict: in (46) with depending on , the residual law depends on . The homogeneous
theorem is kept because its regularity follows from a checkable structural condition and its proof
needs no diagonal: with a fixed factor one sequence serves every order, without the rate coupling
of Lemma 9.8 or the component growth of Remark 9.16.
Remark 9.15 (Finite regularity). If Assumption 9.2 holds only through order on the terminal
edges of a finite maturity set , take and impose (56) on those edges only, the only ones at which
(54) enters (Lemma 9.10); the same proof gives closure in for this finite-regularity class . The
all-order assumption is what yields one sequence converging in the full topology.
Remark 9.16 (Component budget). With the proof needs , . On the schedule , this is below
at , and the component count in (51) grows accordingly — driven by the derivative order, unlike
the homogeneous construction. At a fixed order (, Remark 9.15) the admissible error is up to a
constant.
Corollary 9.17 (Rate at a fixed readout order in the local-SV class).Run the lifted construction with
per-node quantization error and a common innovation variance , and fix a readout order
.
For the error is , so there is no balance to strike. For , if is Hölder-in uniformly in the label, — at read as the distribution function, Lipschitz because is bounded, so — the errors in and are at most , optimized at , giving .
If in addition the target return densities are with bounded derivatives — as in Proposition 9.4, where — the innovation bias is and the balance improves to , giving
Proof.Compare three objects: the target; the smoothed target, whose return from any state over
edges is the target’s return plus an independent ; and the approximant. The error splits into
a quantization part, approximant against smoothed target, and a bias, smoothed target against
target.
Quantization part. From a label , the approximant’s return over edges is the sum of its proxy
increments plus the accumulated innovations, which by (50) have law and are independent of
the proxy-label chain. Coupling the proxy increments with the target’s returns from the point
, as in Theorem 9.9, costs at most in , uniformly in ; the innovations do not enter the proxy recursion, so this cost does not depend on . Lemma 8.2 with the common factor and then
bounds the difference of by at and by for . Only density derivatives of order at most enter,
which is where this differs from a bound through . The exponential moments are uniform by the
tower argument in the proof of Proposition 9.11, and on the window of Assumption 9.3, slightly
enlarged, the jet map of Lemma 2.1 is Lipschitz, as in the proof of Theorem 8.3. The static jets
therefore differ by , uniformly in the label. The same two lemmas, applied to smoothed target
continuations from two states coupled through (39), show that the smoothed jets are Lipschitz
in the state with constant ; no modulus of the target’s own jets in the state is needed.
Rows. The first-edge innovation is independent of the date- label , so the approximant’s row
has numerator , with the first proxy increment, and denominator . Split into the approximant’s
jets against the smoothed jets at , the smoothed jets at against those at , and the smoothed jets
at against the target’s. The first term is the quantization part, the second is at most , and the
third is the bias below, uniform in the state. Hölder’s inequality against the first-edge returns,
which are apart in , and the denominators, which differ by at most and are bounded below by
(45), give the same bound as the jets.
Bias. For a target return from any state and an independent , the call function of is , so . Taylor’s
formula in , whose first two moments are and , gives
when the return density has bounded
derivatives, as in Proposition 9.4, and already when it has , the second-order remainder being ; over
edges, replace by . Under (2) the bias is therefore , uniformly in the state, with a constant controlled
by ; at it is because the density is bounded. Under (1) only the modulus is available and the cruder is
used.
Equating the two parts gives the stated balances; at the quantization part carries no power of , so
no balance arises.∎
One might keep the target’s own floor instead: in Proposition 9.4 the increment splits as
with independent of given the state, and quantizing alone would give the fixed-factor
situation of Section 8. But a finite chain samples its kernel at the finitely valued proxy
label, the target at its own traded log price, and a fixed innovation keeps the two apart.
The proxy enters through the approximant’s filtration, not through the cost: let be the
couplings of and a finite proxy-GM chain that are bicausal for the natural filtration of under
and for under , and put
It charges only the traded price and the mark and is at most
a multiple of the lifted distance of Theorem 9.9, so a lower bound on it is the stronger
statement.
Proposition 9.18 (A non-vanishing innovation obstructs adapted approximation).Let , and
suppose some edge kernel depends on the log price at every mark: for some and some bounded
-Lipschitz , the map
is non-constant for every . If are finite proxy-GM chains whose total
innovation variance before date , , satisfies , then .
Proof.Suppose not; then there are indices, relabelled , and with cost tending to zero. Put and
, which by (50) has law and is independent of . The laws of converge, which is impossible if is
unbounded, since then for every ; so along a further subsequence with . Under , conditionally on
the joint past at date , bicausality and the Markov property make distributed as and as a law
that depends on the proxy label alone, by (48). With and -Lipschitz,
By (39), is -Lipschitz,
so may be replaced by at a cost tending to zero, and . For put with . Since is independent of
, the last expectation is at least . Since is bounded and -Lipschitz, may be restricted to , where
the infimum is attained, and is equicontinuous in uniformly in , the being coupled through
one standard normal; so is continuous. It is positive because has full support: would make the
continuous function equal to the minimizing everywhere. The are tight; a compact with for
all and give , a contradiction.∎
Kernels that do not depend on the log price are homogeneous, and fall under Theorem 7.3 when
they carry a factor (Assumptions 3.1 and 3.2). Keeping the floor of Proposition 9.4 gives , so under
the hypothesis it cannot converge in , and quantizing the floor instead removes the Gaussian
component it was meant to supply (Proposition 2.5). The obstruction concerns adapted
approximation: a fixed innovation can still match finitely many readout coordinates on
one edge (Proposition 10.1), and the vanishing need not be tied to the derivative order
(Proposition 9.20).
Proposition 9.19 (The innovation term is sharp).Let , and suppose there are , a bounded
-Lipschitz , constants and , and a Borel set with , such that whenever and the map is
monotone on with there. Then every finite proxy-GM chain with satisfies
For the chains of
Theorem 9.9, , and with (59) this gives for large : the innovation term of (59) is optimal. The
construction has with , so and its adapted error is of exact order .
Proof.Let have cost , and keep the notation of the proof of Proposition 9.18. The two estimates
at its start give . If , then because . Otherwise Markov’s inequality gives , and ; on the intersection
of with the complements, and , so on this event, of probability at least , lies in the set of
labels within and of a point of . For the map is -monotone on , which contains on the events and , each of probability ; on them lies respectively below and above two values apart, so every
constant is at distance at least from one of them and . Independence of and then gives . Take
the infimum over .∎
Proposition 9.20 (Linear rate when no evaluation follows the readout).Let the target be in
the class of Proposition 9.4with final-edge floor , and let . Run the construction of Theorem 9.9with edge variances for and , the final-edge atoms quantizing the residual alone. Then for every
finite ,
with , and with no diagonal and no order-dependent component budget.
Proof.The static jets at , root and continuation, are functionals of return laws ending at , each
containing common to target and approximant, so Lemma 8.2 gives once the parts before that
factor are apart in . They are: the kernels are evaluated at the proxy, which (25) keeps within of
the target’s log price (on the final edge for the residual, Lipschitz in the state with the same since
the synchronous coupling of Proposition 9.4 makes the floors equal), and the innovations before
the final edge, the only ones preceding a kernel evaluation, have total variance at most . For
the rows, Lemma 8.2 on two synchronously coupled target continuations makes the continuation
jets Lipschitz in the state, and the proof of Theorem 8.3 applies with denominator at least .
Definition 9.6 permits a different variance on each edge, and the jet map is Lipschitz on the
window as in Theorem 8.3.∎
Remark 9.21 (Why the two classes separate quantitatively). Theorem 8.3 keeps fixed, so the
readout error is the quantization error times a constant; Corollary 9.17 must send and pays
even in case (2). With weights on the order- coordinates, a metric compatible with the readout
topology, the error is of order , , with a fixed factor and only with vanishing innovations. Neither
exponent is intrinsic — polynomially decaying weights turn both into logarithms — but the gap
is, being present coordinate by coordinate. All of these are upper bounds; Section 10.1 reports
where they are loose.
10Closed-form readout, cubature and numerics
The readout of a finite chain is available in closed form, which drives the discrete model of [29] and the
computations below; one edge with fixed continuation admits exact finite-order matching by
cubature.
If a normalized log return has the finite mixture law , with and , its call price is, as in [13],
All
strike derivatives are finite sums, so Lemma 2.1 gives the ATM jets by one scalar inversion and implicit
differentiation, and the projected rows follow from the mixture formulas of Section 2.3,
which for branch-constant continuation jets give (29) with variance (homogeneous) or
(proxy).
Proposition 10.1 (One-step finite-order attainment).Fix a current state, one maturity, a
fixed continuation, and the standard pivot . Suppose the target one-step marked return has the
common-variance representation
where and . Write , let be the fixed-continuation jet, and
define
where is the continuation log return from . Assume every coordinate of
is in . For
every , there is a finite mixture with at most components which is an exact asset martingale and
matches exactly the raw static and projected inputs needed to recover .
Proof.Use the displayed vector as the cubature test vector. The common positive Gaussian
variance justifies differentiation under the -integral: Gaussian derivative bounds dominate the
strike derivatives, while the exponential-moment coordinate controls the call value. Including the
constant, the test vector has
coordinates. Tchakaloff’s theorem [6], applied to the law of the
test vector with linear test functions, gives at most that many nodes in its support and positive
weights matching every coordinate. The coordinates depend on only through and are continuous
there, the continuation jets by Propositions 6.5 and 9.11; as bounds along convergent sequences
and is compact, the range on is closed, so every node is the value at some . A martingale version,
with support inside that of the original law, is in [9]. Matching the martingale coordinate gives
. Matching the first two moments and the cross-moments gives the exact regression numerators
and denominator, including the within-component variances. Matching the call derivatives gives the exact static jets through the order needed by the triangular inversion. Hence the recovered
projected velocity jets agree.∎
Proposition 10.1 concerns one edge with fixed continuation and variance, not the constructions,
whose continuations are endogenous.
10.1Two checks of the rates
Take two edges, , and a latent mark on with a smooth density. Conditionally on ,
with fixed by , and
from the continuation return is a two-component Gaussian mixture with skewed means and
-proportional scales, renormalized to unit exponential mean. Both conditional laws are finite mixtures,
so the maturity- jets follow from (67) and Lemma 2.1, and the target readout of (6) is a
one-dimensional quadrature in .
The approximant quantizes the joint law of into cells, mark bands times conditional return
quantiles, so . Cell carries mass , mark and log-barycentre , so at every resolution; the first-edge
return is plus the independent factor, and, the target being homogeneous, the label is the mark
alone.
Table 1. Theorem 8.3 at : readout error against the atom count with the factor variance held
at . Last row: log-log slopes in over the four finest resolutions, against the predicted up to
logarithms.
6
36
13
169
28
784
58
3364
121
14641
175
30625
slope in
Theorem 8.3 assumes a factor of fixed variance, so we split off both edges and hold it fixed, with
on , and vary only the resolution. With and its readout is
and . The continuation is kept exact
at the cell’s mark barycentre, which isolates the quantization error of Lemma 8.1 and its
propagation.
In Table 1, equals one to at every resolution, so martingality is exact rather than asymptotic, and
every measured slope is at least in modulus against a predicted up to logarithms, the ratio
to falling monotonically over the last four rows. The bound therefore holds with room;
the projected rows, which carry the covariance against the quantized edge, track it most
tightly.
The same setup shows where Corollary 9.17 is loose. For a floored return , with and a
two-component mixture, quantized into equal-probability log-barycentric cells and smoothed by as in
Section 9 (worst case over the phase of the cell grid relative to ), the innovation bias is linear in
— over the error grows by factors to against a ratio of , as (66) predicts — and at
the measured error exponent in is at the worst phase and at the median, against from
Corollary 9.17(2). The exponent is right in kind but conservative: equal-probability cells make the
distribution function accurate to before any smoothing, which a bound through cannot
see.
10.2A constrained band on an SPX surface
Figure 1. Forward-start and cliquet values of exact-martingale finite-GM chains that price the
same SPX vanillas inside bid–ask, 28 May 2026. Left: the three-month forward-start smile starting
in one month; the outer band is the range under the vanilla quotes alone, and the inner bands
are the ranges under chains that also match , then , then , pinned at the three-month values
of [18]. Every band is exact: each endpoint is attained by an explicit chain and bounded by a
dual certificate, the two agreeing to within volatility points. The two lines are the chains at the
cliquet endpoints under all three constraints. Right: the same for a two-period cliquet with local
caps floored at zero.
Whether pinning a finite readout says anything about prices is an empirical question, and this
section examines it on one surface in detail and then on sixty month-ends.
Data and fit. SPX end-of-day chains for 28 May 2026 at and years, with and two-sided quotes
and forwards from put–call parity. A two-date chain with and atoms prices all quotes inside their
bid–ask spreads, with implied-volatility errors of and points root mean square, and is a martingale to
.
Experiment. Hold both fitted marginals fixed, so that every quote stays inside bid–ask, and search
over the finite exact-martingale chains that join them, with the fitted atoms and component variances:
a chain is a finite set of first-date branches, each at a fitted location with its own transition law over
the second-date components, , and total masses per location and per component as fitted.
Several branches may share a location — a latent state the price does not reveal — and the
readout then averages their jets (Proposition 7.5). Maximize and minimize the forward-start
implied volatility for at strikes , first under these constraints alone and then adding the
velocity coordinates one at a time, each pinned to the three-month value of [18], , within
.
Computation. Without the readout these are linear programs in the joint weights, the martingale
optimal transport problem of [7, 26] on a finite grid. With it, each branch still enters linearly
— through its mass, its law and its jets , with its continuation call price and first two
strike derivatives at the money and the map of Lemma 2.1 — and so does the velocity
box, since with the date- marginal fixed the velocities are a fixed triangular image of the
rows (8). Each program is thus a linear program over infinitely many candidate branches,
solved by column generation; its optimum is an explicit chain, checked against every bid–ask
interval and the exact readout, so its value is attained. Conversely, weak duality bounds
the largest price by for any multipliers on the second-date weights and on the velocity
box, with the support function of the box and the largest reduced value of one branch at
location ; each is nonconvex only through the three coordinates of and is bounded rigorously
by branch-and-bound over them. Attained values and bounds agree to within volatility
points at every endpoint. Code is available from the authors; the ORATS option data are
proprietary.
Result. On vanillas alone the forward-start smile is undetermined by to volatility points across the
six strikes, at the money (Figure 1). Matching the three readout coordinates as well narrows the
range at every strike, to between and points and to at the money, so that one half to
three quarters of the vanilla range remains; at the money the skew response does most
of the work and the curvature response the least. A two-period cliquet with local caps
floored at zero, resetting at the two quoted expiries so that its periods are and days and
paid at , ranges over basis points on a premium between and of notional, and over with
the three coordinates matched. For a desk this is a measure of residual model risk, not a
model.
Figure 2. The same experiment on the last trading day of each of the sixty months from July 2021
to June 2026, on the whose fit places at least of quotes inside bid–ask. Left: the at-the-money
forward-start range left open by the vanilla quotes, divided into what each coordinate removes as
it is added and what remains with all three pinned at the values of [18], shaded as in Figure 1;
every endpoint is attained by an explicit chain and bounded by a dual certificate, the two agreeing
to volatility points. Right: the fraction removed against the level of volatility, for both targets.
The forward-start fraction does not track that level; the cliquet fraction does, its local caps
binding harder when volatility is high.
Across dates. Run on the last trading day of each of the sixty months from July 2021 to June 2026,
with the two expiries chosen automatically near one and four months and the atom grids scaled to each
surface, the same construction fits of them — on the rest it cannot place of the quotes
inside bid–ask — and gives the same picture on every one (Figure 2): the velocity box is
reachable, attained and certified endpoints agree at the money to volatility points, and
the three coordinates remove a median of the at-the-money vanilla range, quartiles and
and never below , a median points narrowing to ; for the cliquet the median removed
is . The staged picture repeats too: at the money , and remove a median , and of the
total narrowing, and is the largest single step on of the dates, its interval clear of the
other two at every one of them. The pattern across strikes does not: on of the it is the
wing that is narrowed by the largest fraction, a median against at the money, where
this surface has it the other way about. The forward-start figure does not track the level
of volatility (correlation with the one-month at-the-money volatility, which ranges over
to ), whereas the cliquet figure does (), its local caps binding harder when volatility is
high. Holding the component volatility at the of this section instead of a quarter of the
at-the-money volatility fits of the sixty and removes more, a median , with the same staged
ordering.
What is and is not claimed. The ranges are exact over the class searched, and every value between
two endpoints is attained, since mixing two chains branch by branch mixes prices and readouts. Chains
with a single branch per location — continuation a function of the price location alone — can only
have narrower constrained bands; sequential linear programming over them reaches to at
the money, against the exact to . Letting the marginals move within the spreads could
only widen every band. The closest listed forward-starting claim, a VIX future, does not
test the pinned coordinates: its square is a log contract over the whole smile rather than
an at-the-money quantity, and on the VIX calendar of this surface chains matching the
three coordinates still attain to of , against to without them, while strike truncation in
the variance-swap anchors pins the market ratio only to –; the listed VIX prices therefore
neither confirm nor contradict the readout. And the coefficients of [18] are physical-measure
regressions of realized daily moves, whereas is a risk-neutral finite-step projection: they fix the
readout at a plausible magnitude to demonstrate capacity, not to calibrate. Nor does the
narrowing depend on those values: sweeping from to , or and each from zero to twice
the values used, with the other two held, keeps the at-the-money range removed between
and and the cliquet’s between and . It does depend on the readout being a response to
the spot: replacing the regression on the spot move by one on any other contrast across
first-date states, with the jets pinned as tightly relative to their spread, removes at most of the
at-the-money range, whereas pinning spot-dependent moments of the two returns equally
tightly removes about as much as the readout. What narrows the range is pinning how
the continuation law responds to the spot, and the readout records that in quoted implied
volatilities.
11Scope and extensions
Coverage. Imperfect correlation and Lipschitz dependence on the mark are mild; the implied-variance window
and need total volatility bounded above and away from zero; the variance floor of Assumption 3.1 and
a finite-dimensional Markov mark are structural, whereas compactness of and uniform exponential
moments are technical and should yield to localization. Finitely many known roots are handled by a
disjoint union of trees.
Square-root variance. An unregularized square-root variance fails both theorems through degeneracy, not only
noncompactness: localizing to gives a factor of variance as , and one-step density derivatives of order .
The regularizations that restore the hypotheses (Propositions 3.4 and 9.4) are of the kind
implementations commonly apply.
Mark space. An -factor forward-variance model, truncated as in Proposition 3.4, is covered. A curve-valued or
rough mark is not (), although the proofs use only that is compact and convex, as is any
sup-norm-closed set of uniformly bounded curves with a common modulus of continuity.
Fixed marginals. For generic targets the moving-marginal formulation is the strongest one available, not a weakening
(Section 2.6), and with the marginals held at prescribed finite-mixture laws the finite class is capped at
the resolution of the first marginal (Proposition 7.5). A fixed-marginal density theorem can
therefore hold only in a larger class, whose mixing weights depend on the continuous state.
That route rests on stability of martingale couplings, which holds on the line [8, 37, 4]
and fails on [14]; whether it can be carried out with finitely many components per fibre is
open.
Open directions. (i) Instantaneous limit: is a regression over a fixed step; an instantaneous version needs a diagonal
in the mesh. (ii) Noncompact states: Heston-type targets call for Lyapunov localization, as mimicking
already handles degenerate covariance [15]. (iii) Budgets: the bound of Proposition 10.1 is one-step; a
fixed budget yields a capacity profile across orders. (iv) Other readouts: fixed-strike implied
volatilities can be adjoined by (26); for targets with a finite moment index wing slopes cannot
(Proposition 7.4).
12Conclusion
In the topology generated by the dynamics characteristics themselves, for the two target classes,
every
finite order of projected at-the-money smile dynamics is matched to arbitrary accuracy by
exact-martingale finite Gaussian-mixture chains with converging marginals, using the target’s Gaussian
factor (SV) or one manufactured at vanishing variance (LSV). The kernel that generates the dynamics
is never observed; what these statements provide is a licence to search inside a closed-form class, in the
coordinates that are observed, without excluding any finite-order behaviour these models
produce.
Three qualifications travel with that licence. The rate is up to logarithms, with only the latent
dimension in the exponent (Theorem 8.3), and our bound degrades when the Gaussian innovations
must vanish, which adapted approximation forces for innovations preceding a price-dependent kernel
(Proposition 9.18); we do not prove the degradation itself necessary. The licence is at the money:
finite mixtures have zero implied-variance wing slopes, so it does not extend to a readout
containing the wings (Proposition 7.4). And it is a capacity statement, not a calibration
procedure — though on one SPX surface the vanillas leave the at-the-money forward-start
volatility undetermined by points, and fixing the first three characteristics narrows this to
(Section 10.2).
References
[1]Eduardo Abi Jaber and Shaun (Xiaoyuan) Li, Capturing smile dynamics with the quintic volatility model: SPX, skew-stickiness ratio and VIX, arXiv:2503.14158 (2025; revised 2026).
[2]Athanassia Bacharoglou, Approximation of probability distributions by convex mixtures of Gaussian measures, Proceedings of the American Mathematical Society 138 (2010), no. 7, 2619–2628, doi:10.1090/S0002-9939-10-10340-2.
[3]Julio Backhoff-Veraguas, Daniel Bartl, Mathias Beiglböck, and Manu Eder, Adapted Wasserstein distances and stability in mathematical finance, Finance and Stochastics 24 (2020), 601–632; arXiv:1901.07450, doi:10.1007/s00780-020-00426-3.
[4]Julio Backhoff-Veraguas and Gudmund Pammer, Stability of martingale optimal transport and weak optimal transport, Annals of Applied Probability 32 (2022), no. 1, 721–752, doi:10.1214/21-AAP1694.
[5]Daniel Bartl, Mathias Beiglböck, and Gudmund Pammer, The Wasserstein space of stochastic processes, Journal of the European Mathematical Society 28 (2026), no. 1, 393–454; arXiv:2104.14245.
[6]Christian Bayer and Josef Teichmann, The proof of Tchakaloff’s theorem, Proceedings of the American Mathematical Society 134 (2006), 3035–3040, doi:10.1090/S0002-9939-06-08249-9.
[7]Mathias Beiglböck, Pierre Henry-Labordère, and Friedrich Penkner, Model-independent bounds for option prices—a mass transport approach, Finance and Stochastics 17 (2013), 477–501, doi:10.1007/s00780-013-0205-8.
[8]Mathias Beiglböck, Benjamin Jourdain, William Margheriti, and Gudmund Pammer, Approximation of martingale couplings on the line in the adapted weak topology, Probability Theory and Related Fields 183 (2022), no. 1–2, 359–413, doi:10.1007/s00440-021-01103-y.
[9]Mathias Beiglböck and Marcel Nutz, Martingale inequalities and deterministic counterparts, Electronic Journal of Probability 19 (2014), no. 95, 1–15, doi:10.1214/EJP.v19-3270.
[10]Lorenzo Bergomi, Smile dynamics IV, Risk Magazine, December 2009, 94–100.
[12]Lorenzo Bergomi and Julien Guyon, Stochastic volatility’s orderly smiles, Risk, May 2012, 60–66.
[13]Damiano Brigo and Fabio Mercurio, Lognormal-mixture dynamics and calibration to market volatility smiles, International Journal of Theoretical and Applied Finance 5 (2002), no. 4, 427–446, doi:10.1142/S0219024902001511.
[14]Martin Brückerhoff and Nicolas Juillet, Instability of martingale optimal transport in dimension , Electronic Communications in Probability 27 (2022), paper no. 24, doi:10.1214/22-ECP463.
[15]Gerard Brunick and Steven Shreve, Mimicking an Itô process by a solution of a stochastic differential equation, Annals of Applied Probability 23 (2013), no. 4, 1584–1628, doi:10.1214/12-AAP881.
[16]René Carmona and Sergey Nadtochiy, Local volatility dynamic models, Finance and Stochastics 13 (2009), no. 1, 1–48.
[17]René Carmona and Sergey Nadtochiy, Tangent models as a mathematical framework for dynamic calibration, International Journal of Theoretical and Applied Finance 14 (2011), no. 1, 107–135.
[18]Charlie Che and Pradeepta Das, Beyond the skew-stickiness ratio: transport geometry of spot-driven variance surface dynamics, arXiv:2608.12493 (2026).
[19]Rama Cont and Peter Tankov, Financial Modelling with Jump Processes, Chapman & Hall/CRC, Boca Raton, 2004.
[20]Valdo Durrleman, From implied to spot volatilities, Finance and Stochastics 14 (2010), no. 2, 157–177.
[21]Nicole El Karoui, Monique Jeanblanc-Picqué, and Steven E. Shreve, Robustness of the Black and Scholes formula, Mathematical Finance 8 (1998), no. 2, 93–126, doi:10.1111/1467-9965.00047.
[22]Avner Friedman, Partial Differential Equations of Parabolic Type, Prentice-Hall, 1964.
[23]Masaaki Fukasawa, Martingale expansion for stochastic volatility, SIAM Journal on Financial Mathematics 17 (2026), no. 2, SC1–SC12, doi:10.1137/26M1841318; arXiv:2601.09324.
[24]Masaaki Fukasawa, On the skew stickiness ratio, arXiv:2602.05241 (2026).
[25]Siegfried Graf and Harald Luschgy, Foundations of Quantization for Probability Distributions, Lecture Notes in Mathematics 1730, Springer, Berlin, 2000.
[26]Alfred Galichon, Pierre Henry-Labordère, and Nizar Touzi, A stochastic control approach to no-arbitrage bounds given marginals, with an application to lookback options, The Annals of Applied Probability 24 (2014), no. 1, 312–336, doi:10.1214/13-AAP925.
[27]Julien Guyon and Jordan Lekeufack, Volatility is (mostly) path-dependent, Quantitative Finance 23 (2023), no. 9, 1221–1258.
[28]István Gyöngy, Mimicking the one-dimensional marginal distributions of processes having an Itô differential, Probability Theory and Related Fields 71 (1986), 501–516, doi:10.1007/BF00699039.
[29]Shaosai Huang, SANOS-Evolve: a discrete stochastic-local-volatility model for European-option smile dynamics, SSRN working paper no. 7151258 (2026); ssrn.com/abstract=7151258.
[30]Benjamin Jourdain and Gilles Pagès, Quantization and martingale couplings, ALEA, Latin American Journal of Probability and Mathematical Statistics 19 (2022), 1–22; arXiv:2012.10370, doi:10.30757/ALEA.v19-01.
[31]Ioannis Karatzas and Steven E. Shreve, Brownian Motion and Stochastic Calculus, 2nd ed., Graduate Texts in Mathematics 113, Springer, New York, 1991.
[32]Olga A. Ladyzhenskaya, Vsevolod A. Solonnikov, and Nina N. Ural’tseva, Linear and Quasi-linear Equations of Parabolic Type, American Mathematical Society, Providence, RI, 1968.
[33]Roger W. Lee, The moment formula for implied volatility at extreme strikes, Mathematical Finance 14 (2004), no. 3, 469–480, doi:10.1111/j.0960-1627.2004.00200.x.
[34]Philipp J. Schönbucher, A market model for stochastic implied volatility, Philosophical Transactions of the Royal Society of London A 357 (1999), no. 1758, 2071–2092.
[35]Martin Schweizer and Johannes Wissel, Term structures of implied volatilities: absence of arbitrage and existence results, Mathematical Finance 18 (2008), no. 1, 77–114.
[36]Cédric Villani, Optimal Transport: Old and New, Grundlehren Math. Wiss. 338, Springer, 2009.
[37]Johannes Wiesel, Continuity of the martingale optimal transport problem on the real line, Annals of Applied Probability 33 (2023), no. 6A, 4645–4692, doi:10.1214/22-AAP1928.
How to cite
Zeyu Cao and Shaosai Huang (2026). Finite Gaussian-mixture martingale kernels: density for projected smile-jet readouts. Working paper, version of September 2026. Kspectra Research. SSRN 7444340 (doi:10.2139/ssrn.7444340). https://kspectra.ai/papers/finite-gaussian-mixture-kernels/
@misc{cao2026finite,
author = {Cao, Zeyu and Huang, Shaosai},
title = {{Finite Gaussian-mixture martingale kernels: density for projected smile-jet readouts}},
year = {2026},
month = sep,
note = {Working paper, version of September 2026},
doi = {10.2139/ssrn.7444340},
url = {https://kspectra.ai/papers/finite-gaussian-mixture-kernels/}
}